

Agilysys has had an impressive run over the past six months as its shares have beaten the S&P 500 by 12.7%. The stock now trades at $96.31, marking a 33.8% gain. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Agilysys, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Agilysys Not Exciting?
We’re happy investors have made money, but we don’t have much confidence in Agilysys. Here are three reasons we avoid AGYS, plus one stock we’d rather own.
1. Low Gross Margin Reveals Weak Structural Profitability
For software companies like Agilysys, gross profit tells us how much money remains after paying for the base cost of products and services (typically servers, licenses, and certain personnel). These costs are usually low as a percentage of revenue, explaining why software is more lucrative than other sectors.
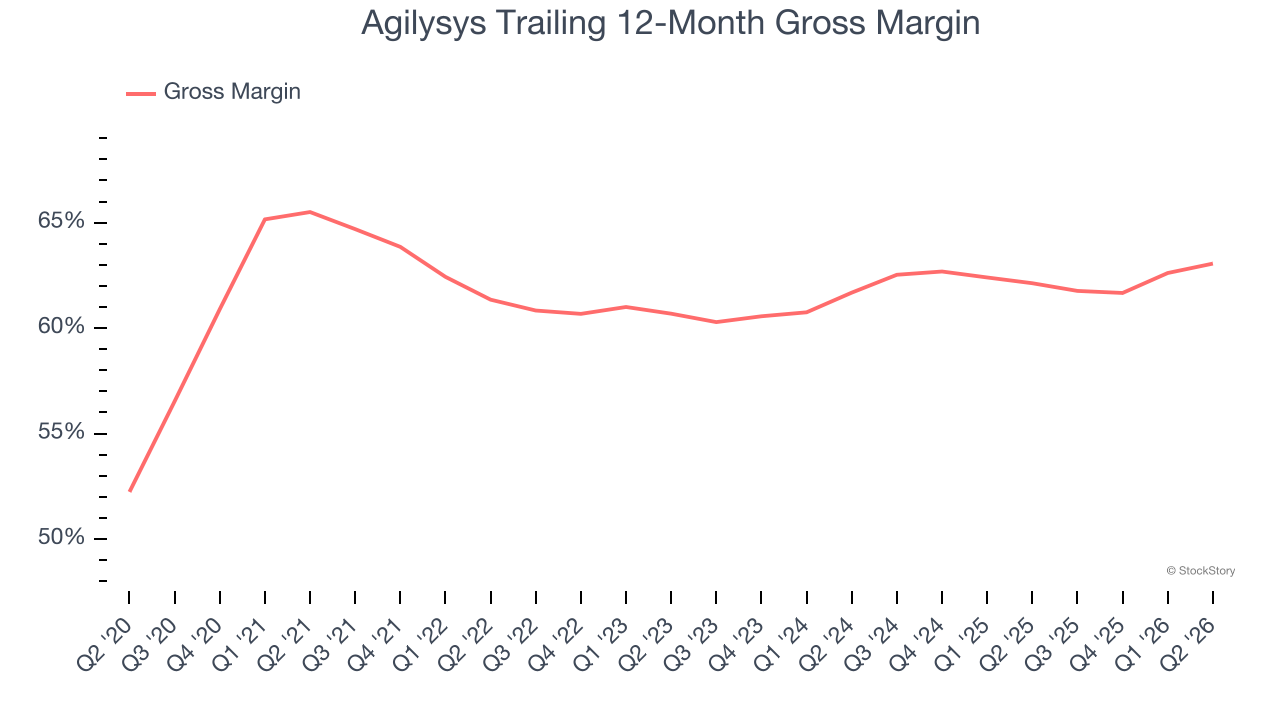
Agilysys’s gross margin is substantially worse than most software businesses, signaling it has relatively high infrastructure costs compared to asset-lite businesses like ServiceNow. As you can see below, it averaged a 63.1% gross margin over the last year. That means Agilysys paid its providers a lot of money ($36.94 for every $100 in revenue) to run its business.
The market not only cares about gross margin levels but also how they change over time because expansion creates firepower for profitability and free cash generation. Agilysys has seen gross margins improve by 1.4 percentage points over the last 2 years, which is solid in the software space.
2. Operating Margin Rising, Profits Up
While many software businesses point investors to their adjusted profits, which exclude stock-based compensation (SBC), we prefer GAAP operating margin because SBC is a legitimate expense used to attract and retain talent. This metric shows how much revenue remains after accounting for all core expenses — everything from the cost of goods sold to sales and R&D.
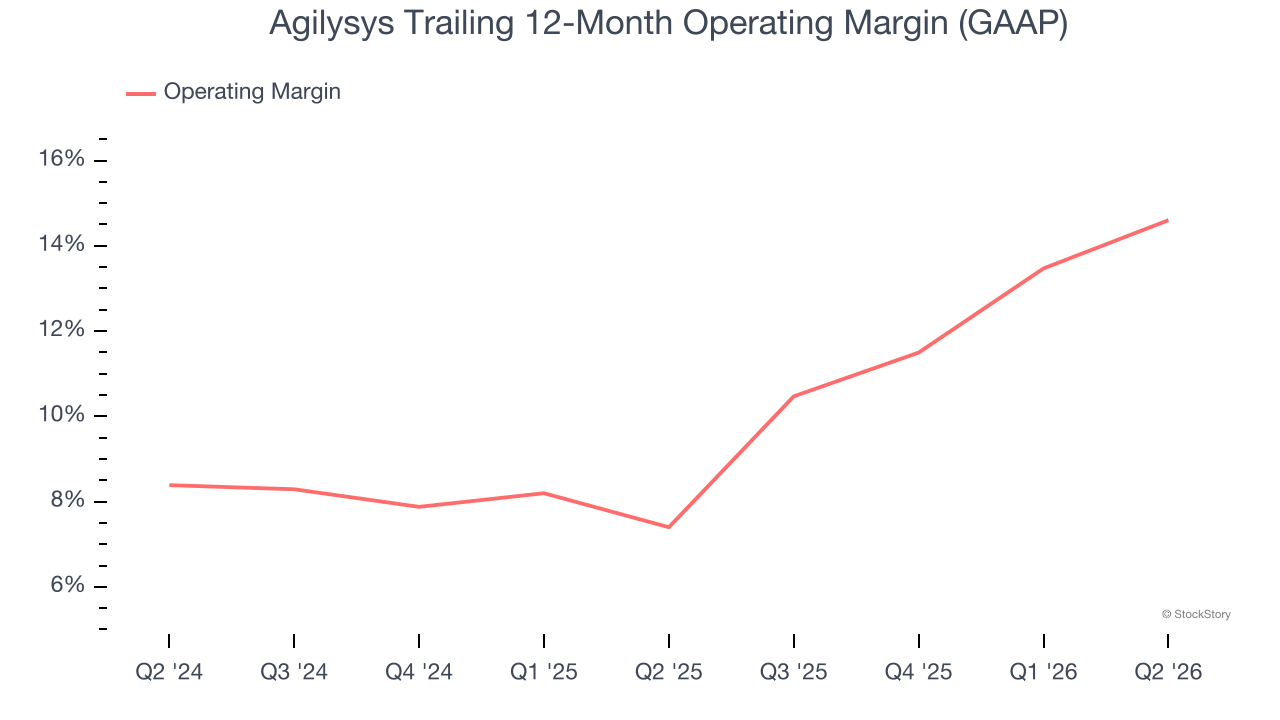
Analyzing the trend in its profitability, Agilysys’s operating margin rose by 7.2 percentage points over the last two years, as its sales growth gave it operating leverage. Its operating margin for the trailing 12 months was 14.6%.
3. Cash Flow Margin Set to Decline
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Over the next year, analysts predict Agilysys’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 24.4% for the last 12 months will decrease to 21.3%.
Final Judgment
Agilysys isn’t a terrible business, but it doesn’t pass our bar. With its shares beating the market recently, the stock trades at 7.1× forward price-to-sales (or $96.31 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. We’d suggest looking at a safe-and-steady industrials business benefiting from an upgrade cycle.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.