
Flywire has been on fire lately. In the past six months alone, the company’s stock price has rocketed 50.8%, reaching $17.33 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is it too late to buy FLYW? Find out in our full research report, it’s free.
Why Does FLYW Stock Spark Debate?
Initially created to solve the challenges of international student tuition payments, Flywire (NASDAQ:FLYW) provides specialized payment processing and software solutions that help educational institutions, healthcare systems, travel companies, and businesses manage complex payments.
Two Things to Like:
1. Billings Surge, Boosting Cash On Hand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Flywire’s billings punched in at $161.6 million in Q2, and over the last four quarters, its year-on-year growth averaged 33.9%. This performance was fantastic, indicating robust customer demand. The high level of cash collected from customers also enhances liquidity and provides a solid foundation for future investments and growth. 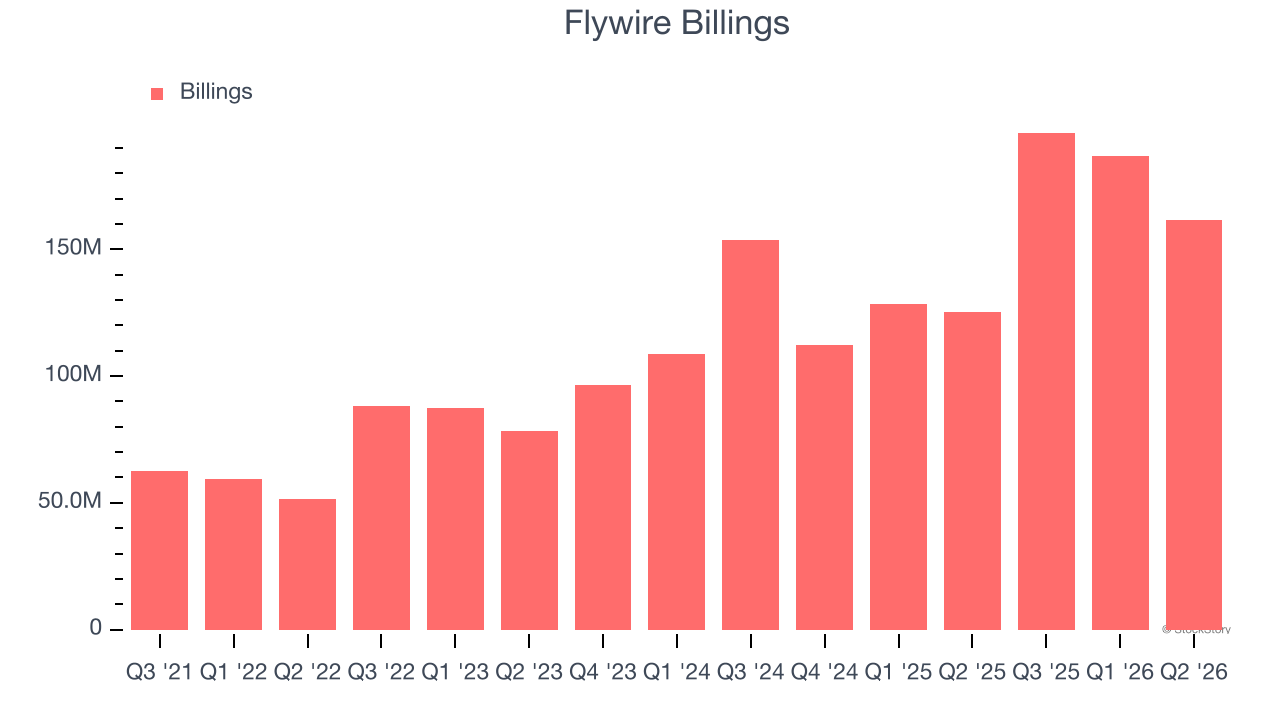
2. Impressive Free Cash Flow Margin Opens Growth Opportunities
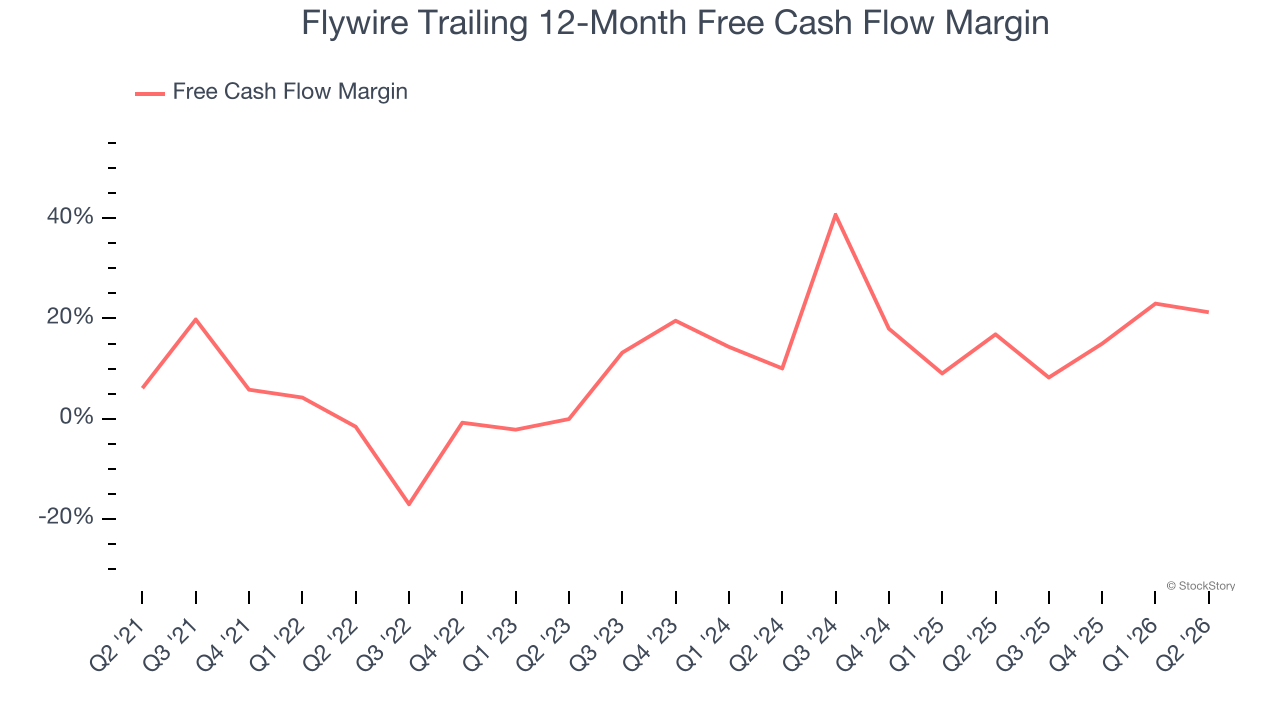
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Flywire has shown impressive cash profitability, giving it the option to reinvest or return capital to investors. The company’s free cash flow margin averaged 21.3% over the last year, better than the broader software sector.
One Reason to Be Careful:
Long Payback Periods Delay Returns
The customer acquisition cost (CAC) payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
Flywire’s recent customer acquisition efforts haven’t yielded returns as its CAC payback period was negative this quarter, meaning its incremental sales and marketing investments outpaced its revenue. The company’s inefficiency indicates it operates in a competitive market and must continue investing to grow.
Final Judgment
Flywire has huge potential even though it has some open questions, and after the recent rally, the stock trades at 2.6× forward price-to-sales (or $17.33 per share). Is now a good time to buy despite the apparent froth? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.