
While the S&P 500 is up 18.4% since March 2026, Eastern Bank (currently trading at $21.15 per share) has lagged behind, posting a return of 10.5%. This might have investors contemplating their next move.
Is now the time to buy Eastern Bank, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Eastern Bank Not Exciting?
We’re cautious about Eastern Bank. Here are three reasons you should be careful with EBC, plus one stock we’d rather own.
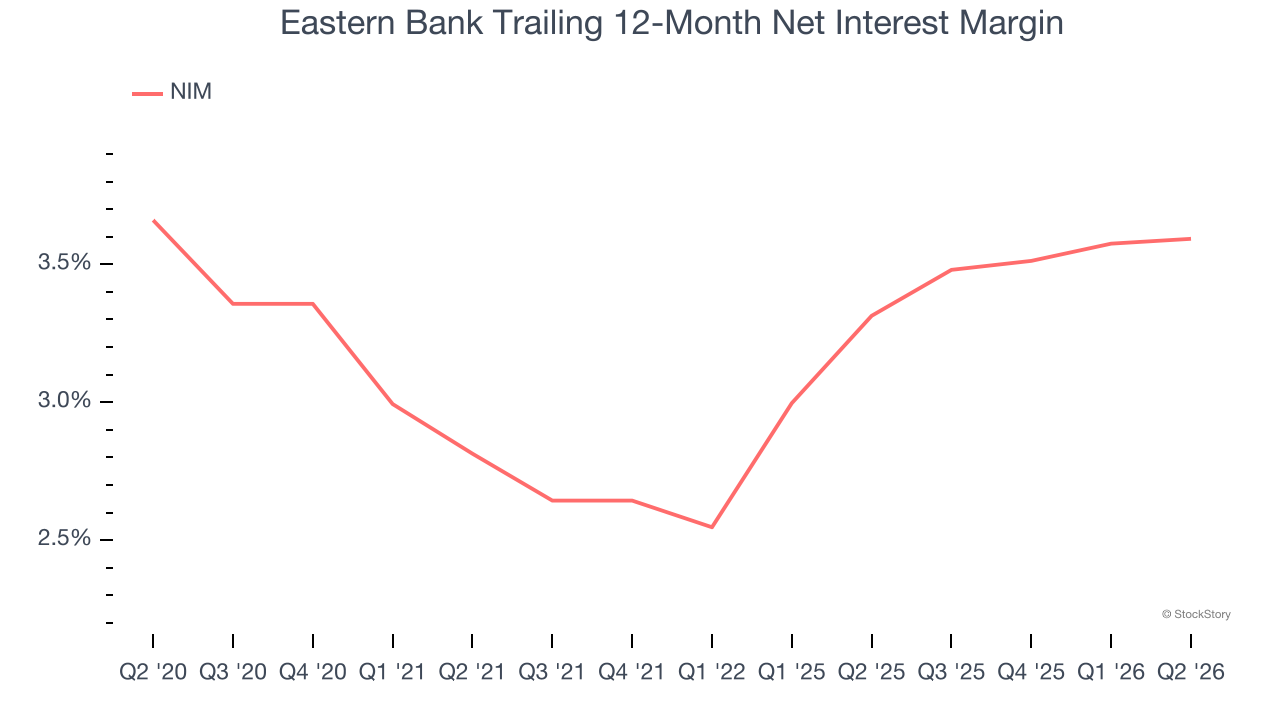
1. Low Net Interest Margin Hinders Flexibility
Net interest margin (NIM) serves as a critical gauge of a bank’s fundamental profitability by showing the spread between interest income and interest expenses. It’s essential for understanding whether a firm can sustainably generate returns from its lending operations.
Over the past two years, we can see that Eastern Bank’s net interest margin averaged a subpar 3.5%, reflecting its high servicing and capital costs.
2. Declining TBVPS Reflects Erosion of Asset Value
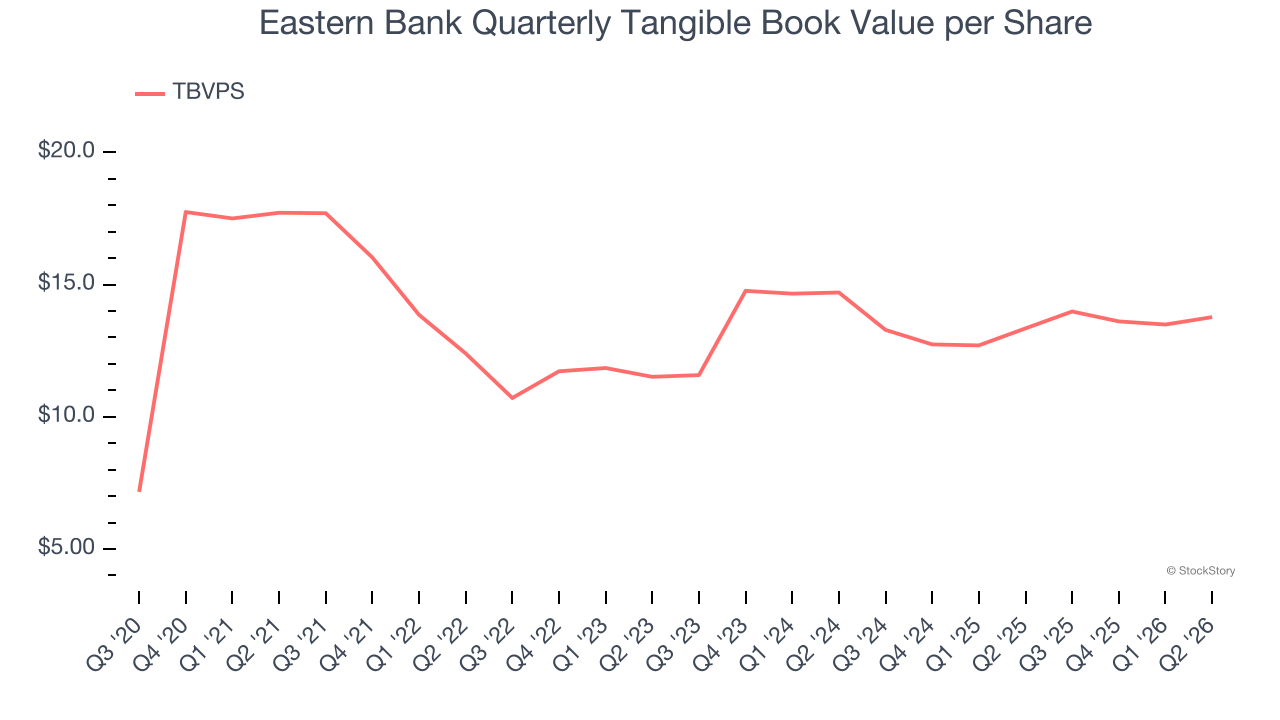
In the banking industry, tangible book value per share (TBVPS) provides the clearest picture of shareholder value, as it focuses on concrete assets while excluding intangible items that may not hold value during challenging times.
To the detriment of investors, Eastern Bank’s TBVPS declined at a 3.2% annual clip over the last two years.
3. Previous Growth Initiatives Haven’t Impressed
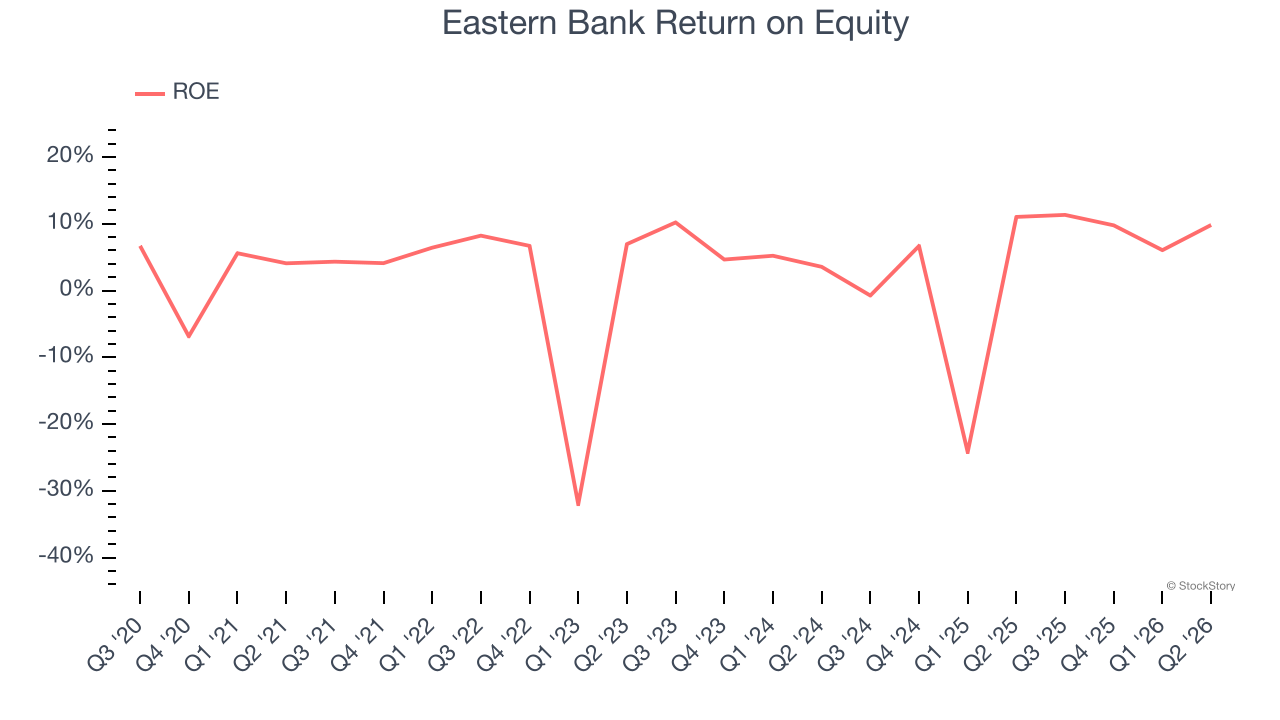
Return on equity, or ROE, quantifies bank profitability relative to shareholder equity - an essential capital source for these institutions. Over extended periods, superior ROE performance drives faster shareholder wealth compounding through reinvestment, share repurchases, and dividend growth.
Over the last five years, Eastern Bank has averaged an ROE of 3.1%, uninspiring for a company operating in a sector where the average shakes out around 10%.
Final Judgment
Eastern Bank isn’t a terrible business, but it doesn’t pass our bar. With its shares underperforming the market lately, the stock trades at 1.1× forward P/B (or $21.15 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at an all-weather company that owns household favorite Taco Bell.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.