

As the Q2 earnings season comes to a close, it’s time to take stock of this quarter’s best and worst performers in the u.s. shale e&p industry, including Cactus (NYSE:WHD) and its peers.
US shale oil producers extract crude from tight rock formations using horizontal drilling and hydraulic fracturing (fracking) techniques, primarily in basins like the Permian, Bakken, and Eagle Ford. Tailwinds include short-cycle investment flexibility allowing rapid production adjustments, technological improvements enhancing well productivity, and proximity to refining and export infrastructure. Capital discipline has improved financial returns. Headwinds include commodity price sensitivity affecting drilling economics, accelerating well decline rates requiring continuous capital investment, and increasing regulatory and ESG scrutiny. Water usage, induced seismicity concerns, and evolving environmental regulations present ongoing operational challenges.
The 11 u.s. shale e&p stocks we track reported an exceptional Q2. As a group, revenues beat analysts’ consensus estimates by 10.4%.
Luckily, u.s. shale e&p stocks have performed well with share prices up 14.5% on average since the latest earnings results.
Cactus (NYSE:WHD)
Named for the spiky wellhead equipment that reminded founders of desert cacti, Cactus (NYSE:WHD) manufactures wellheads, valves, and spoolable pipes used in drilling and producing oil and gas wells.
Cactus reported revenues of $449.5 million, up 64.3% year on year. This print exceeded analysts’ expectations by 12.3%. Overall, it was an incredible quarter for the company with a beat of analysts’ EPS estimates and an impressive beat of analysts’ EBITDA estimates.
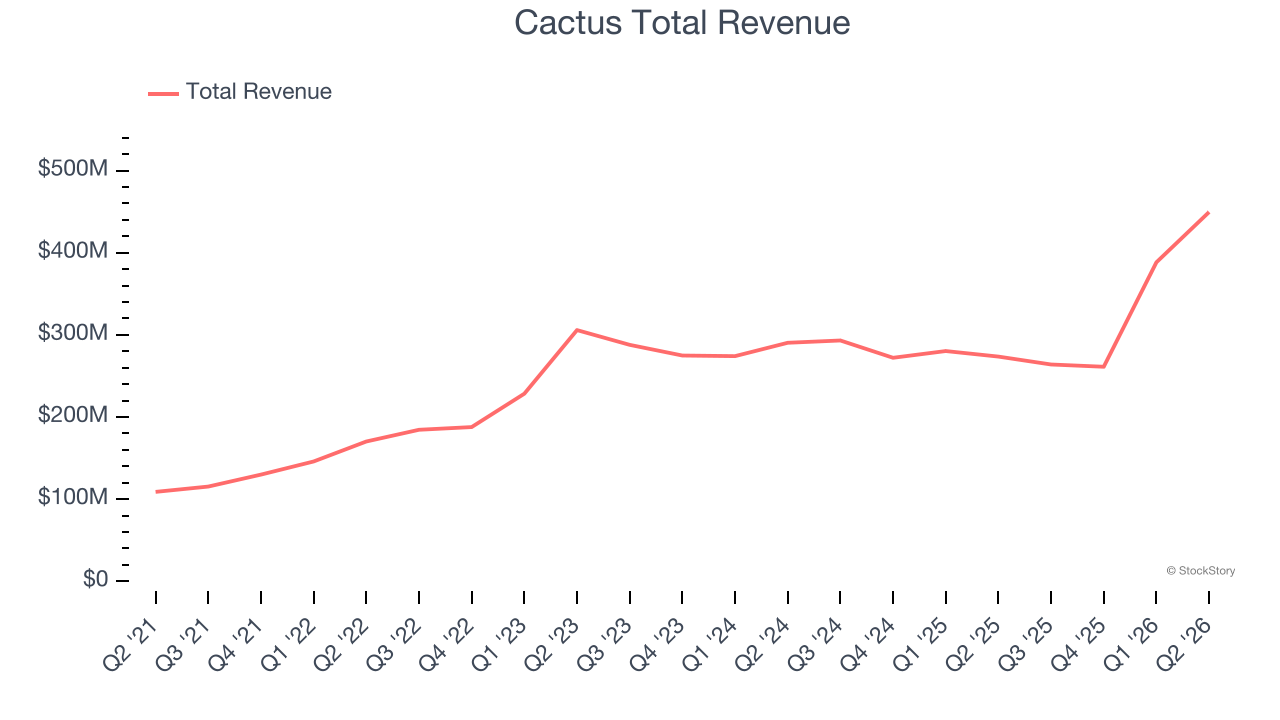
Interestingly, the stock is up 28.5% since reporting and currently trades at $67.25.
We think Cactus is a good business, but is it a buy today? Read our full report here, it’s free.
HighPeak Energy (NASDAQ:HPK)
Operating in the oil-rich northeastern corner of the Midland Basin where Howard and Borden counties meet, HighPeak Energy (NASDAQ:HPK) explores for, develops, and produces crude oil, natural gas liquids, and natural gas.
HighPeak Energy reported revenues of $272.4 million, up 25.8% year on year, outperforming analysts’ expectations by 8.7%. The business had an incredible quarter with a beat of analysts’ EPS estimates.
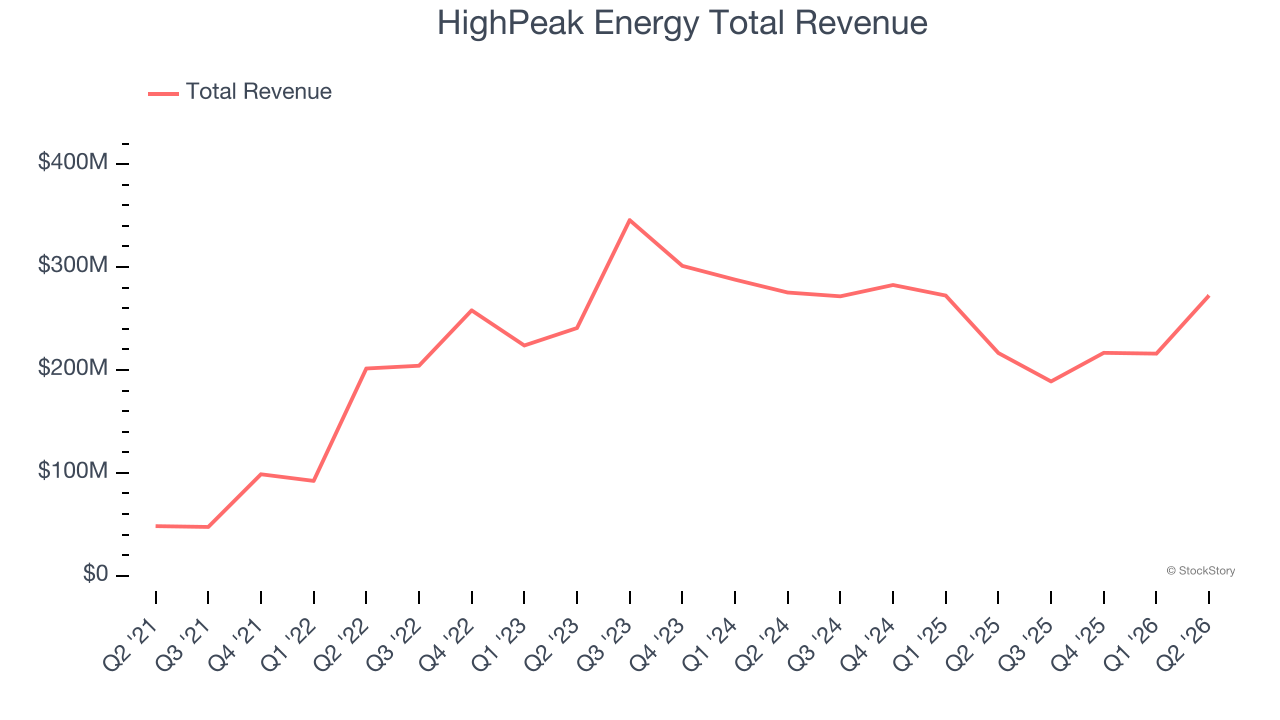
However, the results were likely priced into the stock as it’s traded sideways since reporting. Shares currently sit at $7.93.
Is now the time to buy HighPeak Energy? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Texas Pacific Land (NYSE:TPL)
One of America's largest private landowners with roughly 868,000 acres in the Permian Basin, Texas Pacific Land (NYSE:TPL) owns land in West Texas and earns revenue from oil and gas royalties, water services, and land leases.
Texas Pacific Land reported revenues of $246.1 million, up 31.2% year on year, falling short of analysts’ expectations by 1.4%. It was a mixed quarter as it posted a decent beat of analysts’ EBITDA estimates.
Texas Pacific Land delivered the weakest performance against analyst estimates in the group. As expected, the stock is down 8.4% since the results and currently trades at $349.94.
Read our full analysis of Texas Pacific Land’s results here.
Riley Exploration Permian (NYSE:REPX)
Operating in counties where legacy oil fields have been producing since the early 1900s, Riley Exploration Permian (NYSE:REPX) drills for and produces oil and natural gas from horizontal wells in the Permian Basin of West Texas and New Mexico.
Riley Exploration Permian reported revenues of $165.9 million, up 94.2% year on year. This print surpassed analysts’ expectations by 11.8%. Overall, it was a strong quarter for the company.
The stock is up 30.6% since reporting and currently trades at $43.11.
Read our full, actionable report on Riley Exploration Permian here, it’s free.
Crescent Energy (NYSE:CRGY)
Controlling over 1.4 million net acres across proven U.S. basins, Crescent Energy (NYSE:CRGY) extracts oil and natural gas from underground reservoirs in Texas and the Rocky Mountains.
Crescent Energy reported revenues of $1.39 billion, up 55.3% year on year. This result beat analysts’ expectations by 6.3%. It was a stunning quarter as it also logged a beat of analysts’ EPS estimates.
The stock is up 26.3% since reporting and currently trades at $14.44.
Read our full, actionable report on Crescent Energy here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.