
What a time it’s been for Everpure. In the past six months alone, the company’s stock price has increased by a massive 54.9%, reaching $98.27 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is it too late to buy P? Find out in our full research report, it’s free.
Why Is P a Good Business?
Founded in 2009 as a pioneer in enterprise all-flash storage technology, Everpure (NYSE:P) provides all-flash data storage hardware and software that helps organizations manage their data more efficiently across on-premises and cloud environments.
1. ARR Surges as Recurring Revenue Flows In
We can better understand Hardware & Infrastructure companies by analyzing their ARR, or annual recurring revenue. This metric shows how much Everpure expects to collect from its existing customer base in the next 12 months, giving visibility into its future revenue streams.
Everpure’s ARR punched in at $2.13 billion in the latest quarter, and over the last two years, its year-on-year growth averaged 18.7%. This performance was fantastic and shows that customers are willing to take multi-year bets on the company’s product offerings. Its growth also makes Everpure a more predictable business, a tailwind for its valuation as investors typically prefer businesses with recurring revenue. 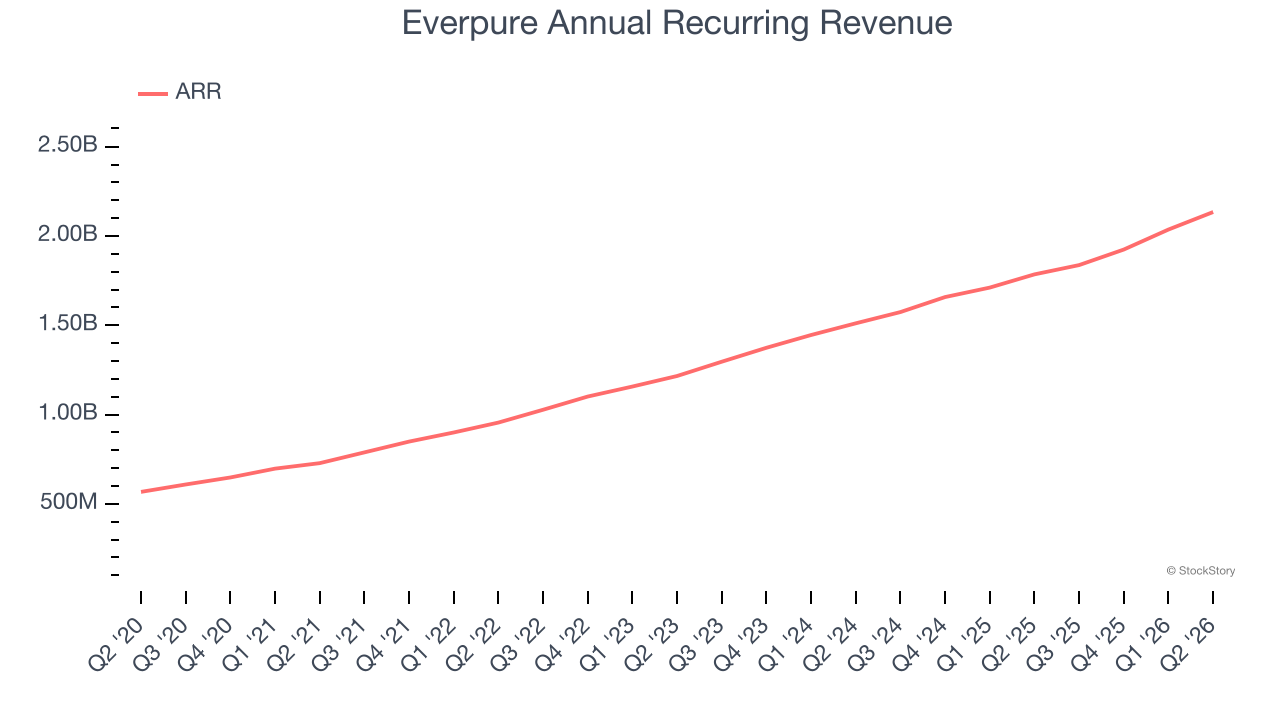
2. Projected Revenue Growth Is Remarkable
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite, though some deceleration is natural as businesses become larger.
Over the next 12 months, sell-side analysts expect Everpure’s revenue to rise by 31.9%, an improvement versus its 18.5% annualized growth for the past five years. This projection is eye-popping and implies its newer products and services will catalyze better top-line performance.
3. Outstanding Long-Term EPS Growth
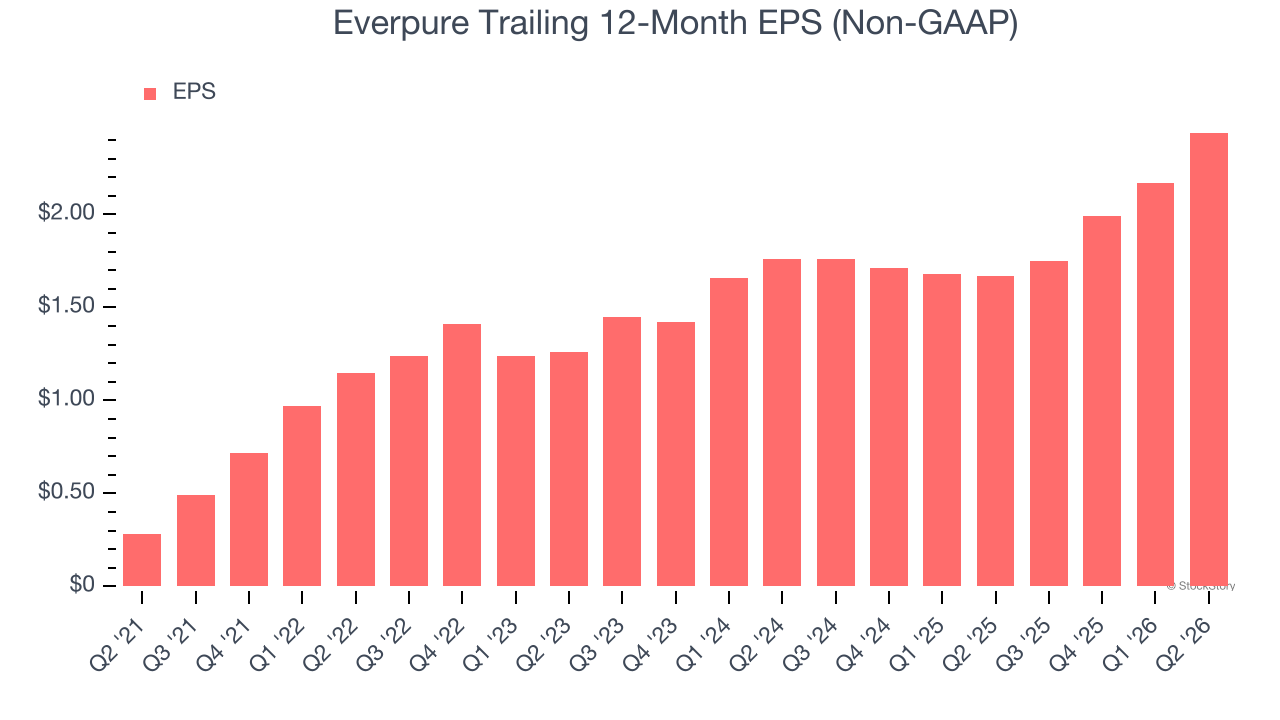
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Everpure’s EPS grew at 54.2% compounded annual growth rate over the last five years, higher than its 18.5% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
Final Judgment
These are just a few reasons why Everpure is one of the best business services companies out there, and with the recent rally, the stock trades at 31.7× forward P/E (or $98.27 per share). Is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.