
The past six months have been a windfall for Paycom’s shareholders. The company’s stock price has jumped 80.7%, hitting $223.12 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now the time to buy Paycom, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Paycom Not Exciting?
We’re happy investors have made money, but we don’t have much confidence in Paycom. Here are three reasons why there are better opportunities than PAYC, plus one stock we’d rather own.
1. Weak Billings Point to Soft Demand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Paycom’s billings came in at $530 million in Q2, and over the last four quarters, its year-on-year growth averaged 9%. This performance was underwhelming and suggests that increasing competition is causing challenges in acquiring/retaining customers. 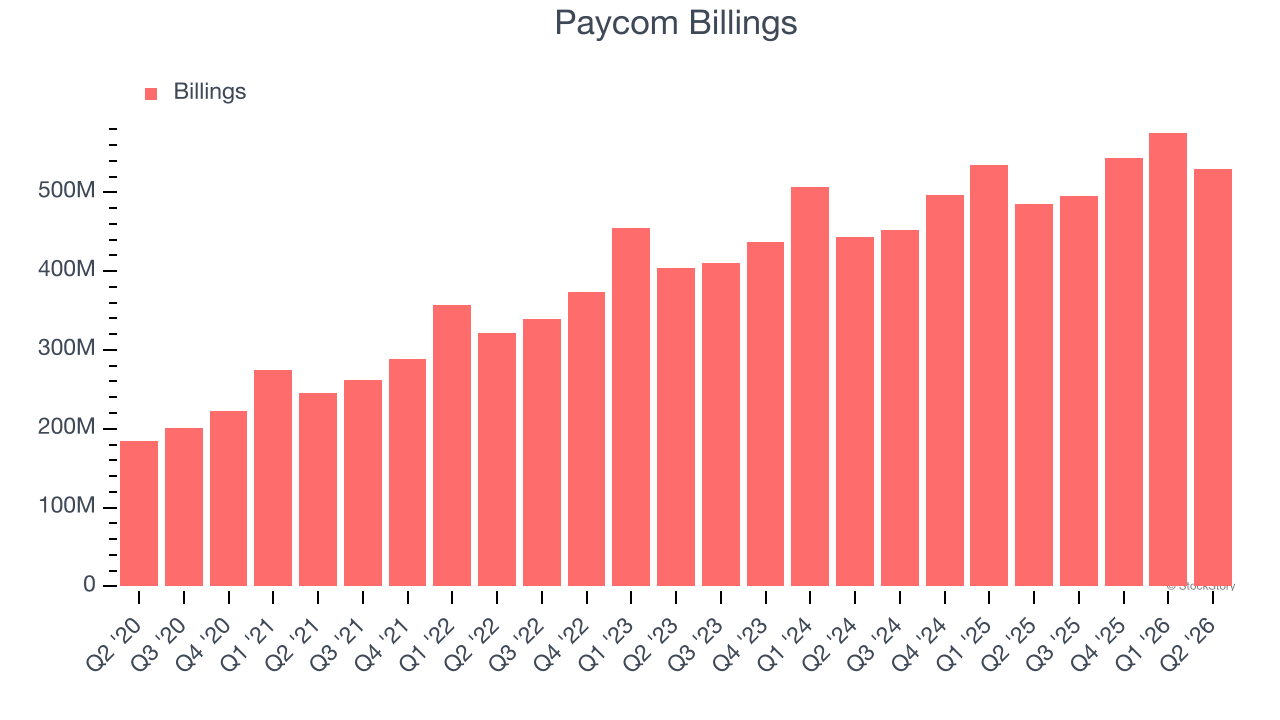
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Paycom’s revenue to rise by 7%, a slight deceleration versus its 18.1% annualized growth for the past five years. This projection is underwhelming and implies its products and services will see some demand headwinds.
3. Operating Margin Rising, Profits Up
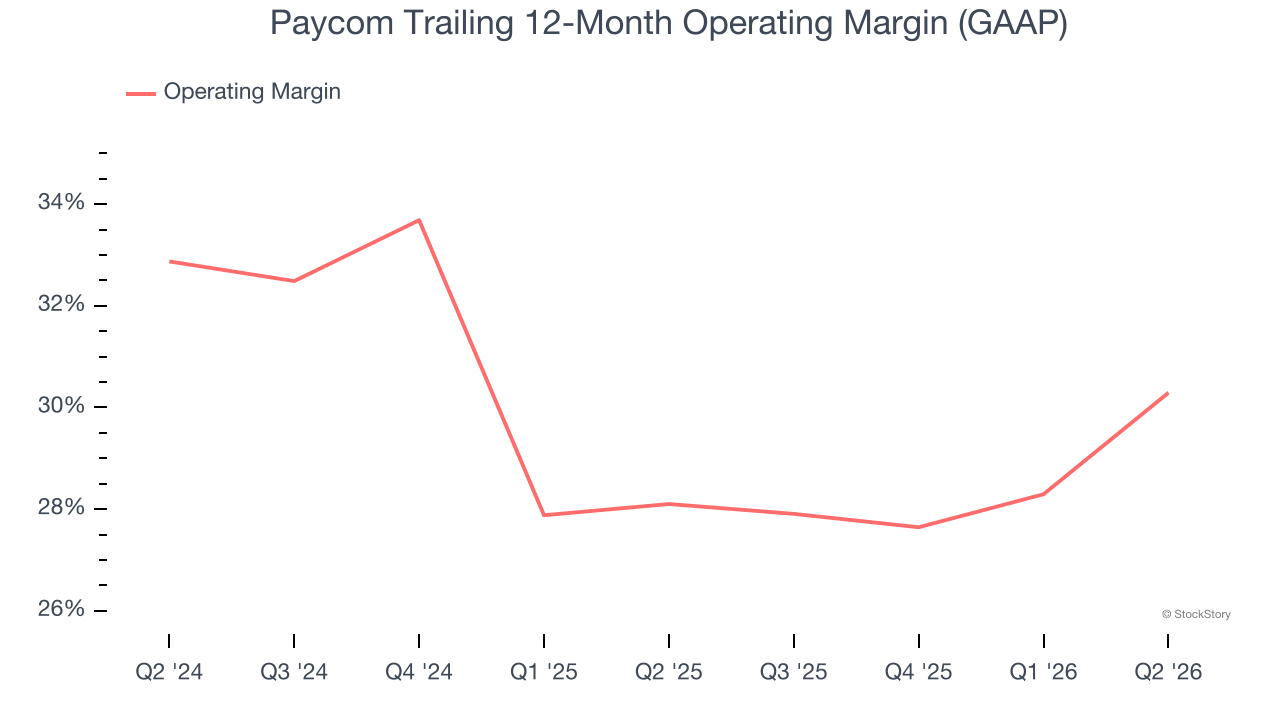
While many software businesses point investors to their adjusted profits, which exclude stock-based compensation (SBC), we prefer GAAP operating margin because SBC is a legitimate expense used to attract and retain talent. This metric shows how much revenue remains after accounting for all core expenses — everything from the cost of goods sold to sales and R&D.
Analyzing the trend in its profitability, Paycom’s operating margin rose by 2.2 percentage points over the last two years, as its sales growth gave it operating leverage. Its operating margin for the trailing 12 months was 30.3%.
Final Judgment
Paycom isn’t a terrible business, but it doesn’t pass our bar. After the recent rally, the stock trades at 4.4× forward price-to-sales (or $223.12 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. We’d recommend looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Would Buy Instead of Paycom
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.