
What a fantastic six months it’s been for Veeva Systems. Shares of the company have skyrocketed 43%, hitting $265. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now still a good time to buy VEEV? Or are investors being too optimistic? Find out in our full research report, it’s free.
Why Does Veeva Systems Spark Debate?
Originally named "Verticals onDemand" before rebranding in 2009, Veeva Systems (NYSE:VEEV) provides cloud software, data solutions, and consulting services that help life sciences companies develop and bring products to market more efficiently.
Two Positive Attributes:
1. Billings Growth Boosts Cash On Hand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Veeva Systems’s billings punched in at $760.9 million in Q2, and over the last four quarters, its year-on-year growth averaged 17.8%. This performance was solid, indicating robust customer demand. The cash collected from customers also enhances liquidity and provides a solid foundation for future investments and growth. 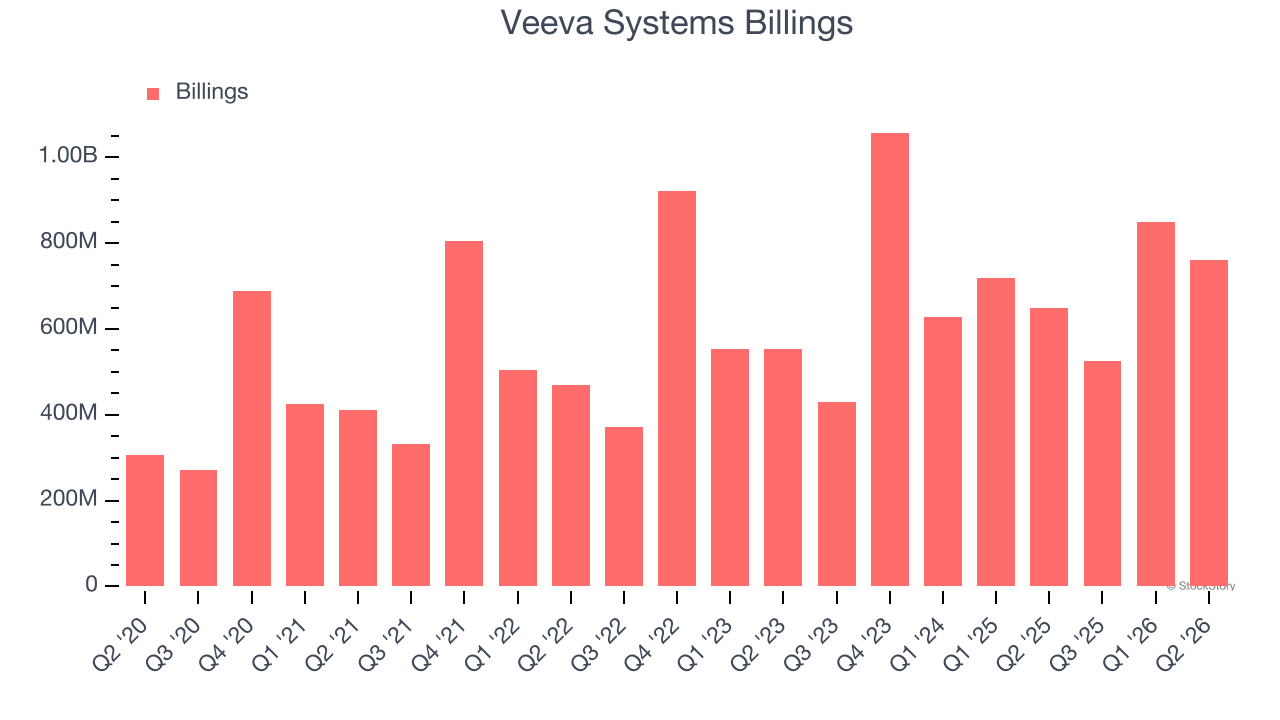
2. Customer Acquisition Costs Are Recovered in Record Time
The customer acquisition cost (CAC) payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
Veeva Systems is extremely efficient at acquiring new customers, and its CAC payback period checked in at 14.2 months this quarter. The company’s rapid recovery of its customer acquisition costs indicates it has a highly differentiated product offering and a strong brand reputation. These dynamics give Veeva Systems more resources to pursue new product initiatives while maintaining the flexibility to increase its sales and marketing investments. 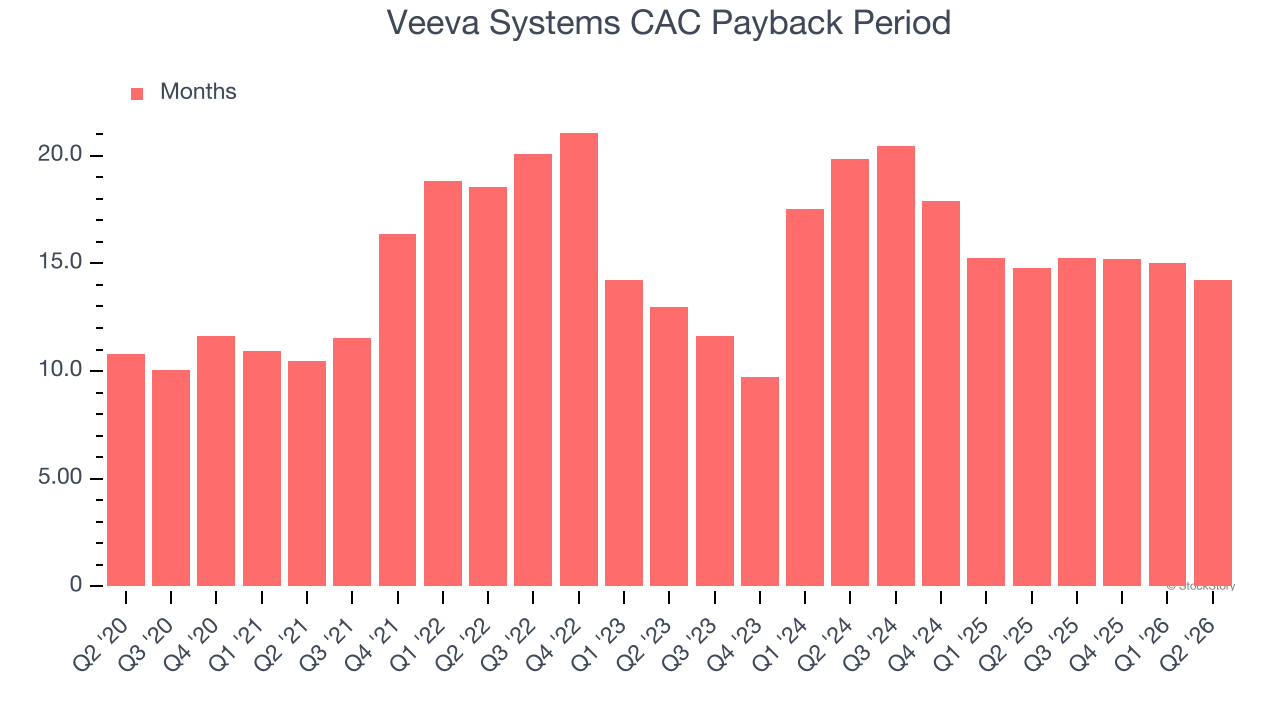
One Reason to Be Careful:
Long-Term Revenue Growth Disappoints
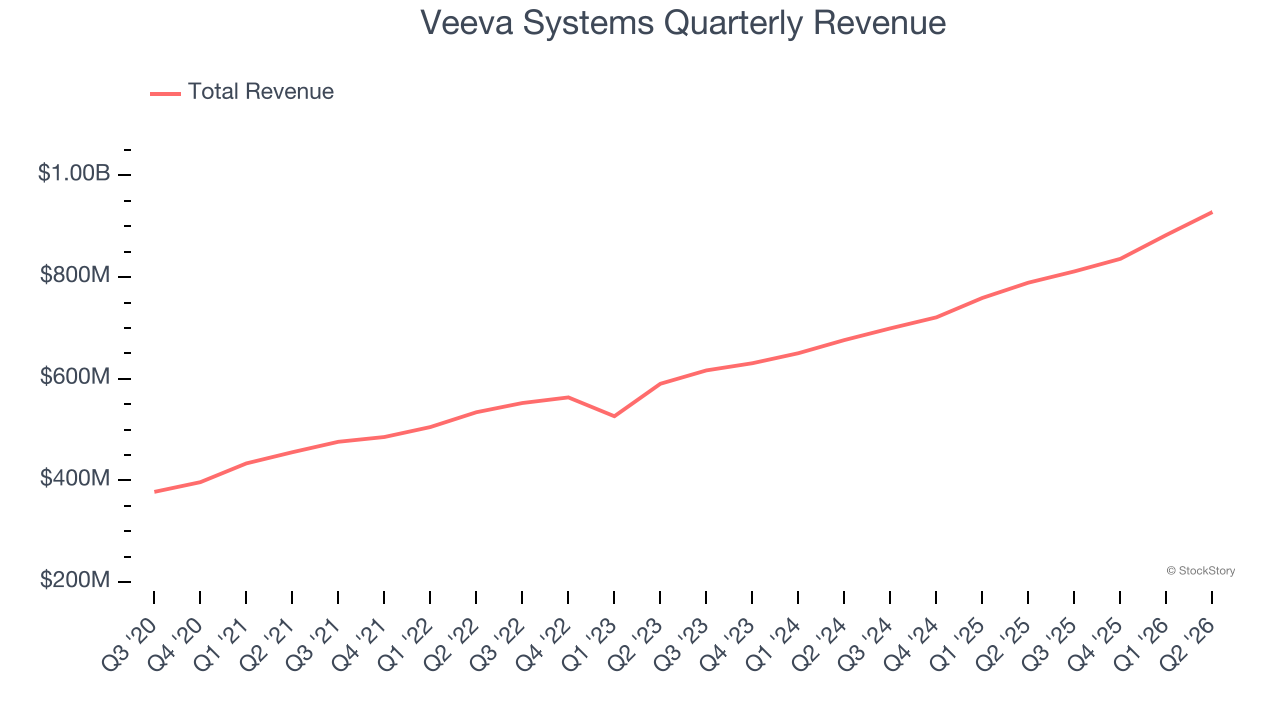
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last five years, Veeva Systems grew its sales at a 15.8% compounded annual growth rate. Although this growth is acceptable on an absolute basis, it fell slightly short of our standards for the software sector, which enjoys a number of secular tailwinds. Luckily, there are other things to like about Veeva Systems.
Final Judgment
Veeva Systems’s positive characteristics outweigh the negatives, and after the recent rally, the stock trades at 11.1× forward price-to-sales (or $265 per share). Is now a good time to buy? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than Veeva Systems
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.