

Distribution Solutions’s 26.6% return over the past six months has outpaced the S&P 500 by 12.3%, and its stock price has climbed to $35.07 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now still a good time to buy DSGR? Or is this a case of a company fueled by heightened investor enthusiasm? Find out in our full research report, it’s free.
Why Does DSGR Stock Spark Debate?
Founded in 1952, Distribution Solutions (NASDAQ:DSGR) provides supply chain solutions and distributes industrial, safety, and maintenance products to various industries.
Two Positive Attributes:
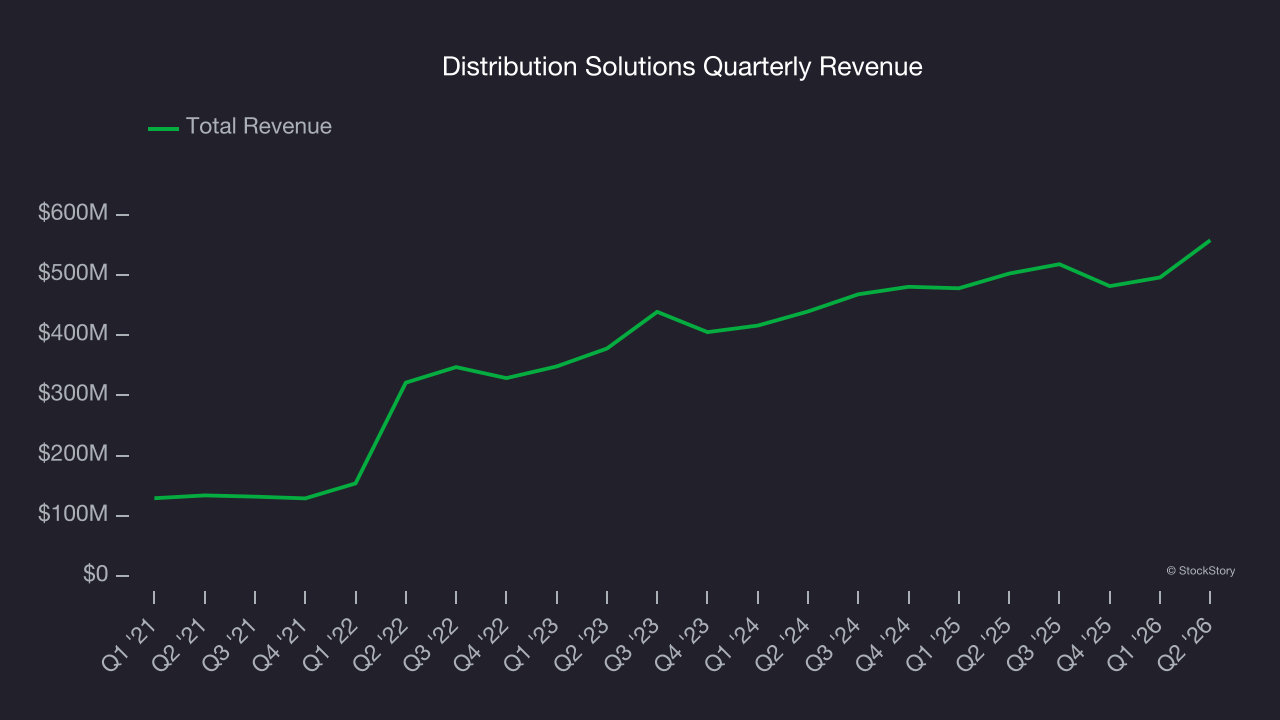
1. Skyrocketing Revenue Shows Strong Momentum
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Luckily, Distribution Solutions’s sales grew at an incredible 31.9% compounded annual growth rate over the last five years. Its growth beat the average industrials company and shows its offerings resonate with customers.
2. Increasing Free Cash Flow Margin Juices Financials
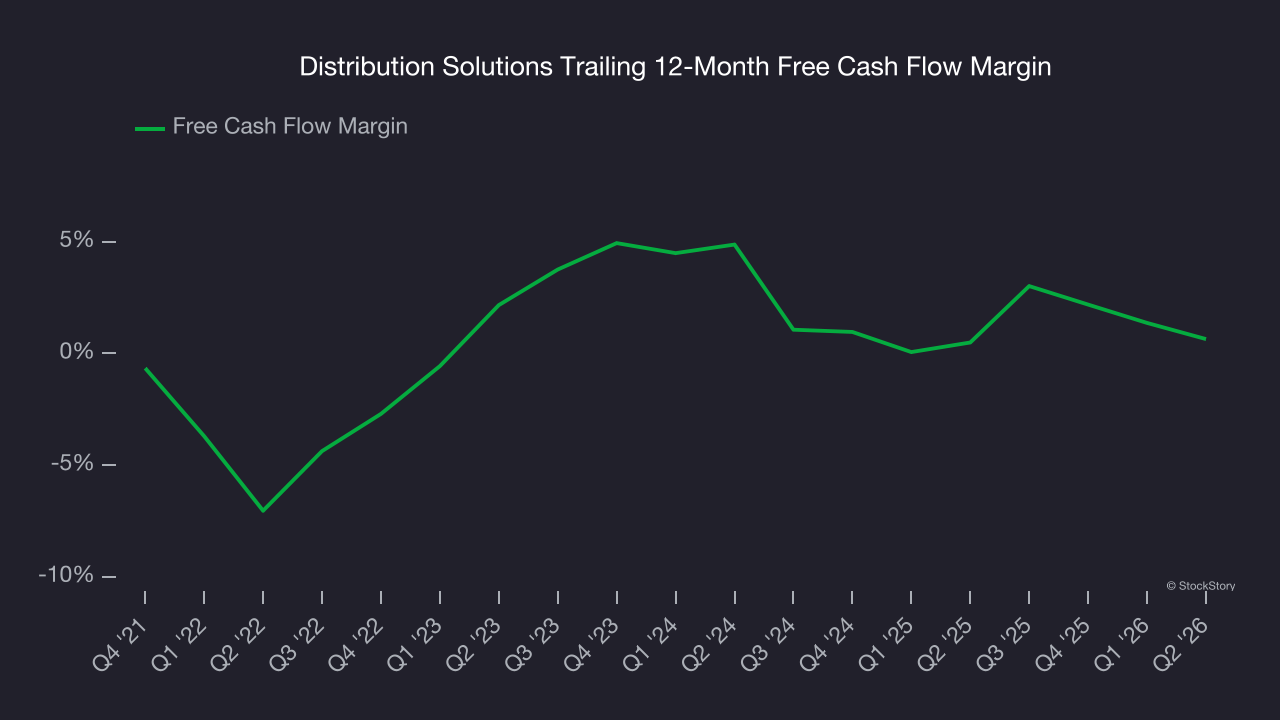
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, Distribution Solutions’s margin expanded by 7.7 percentage points over the last five years. The company’s improvement shows it’s heading in the right direction, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Distribution Solutions’s free cash flow margin for the trailing 12 months was breakeven.
One Reason to Be Careful:
Previous Growth Initiatives Haven’t Impressed
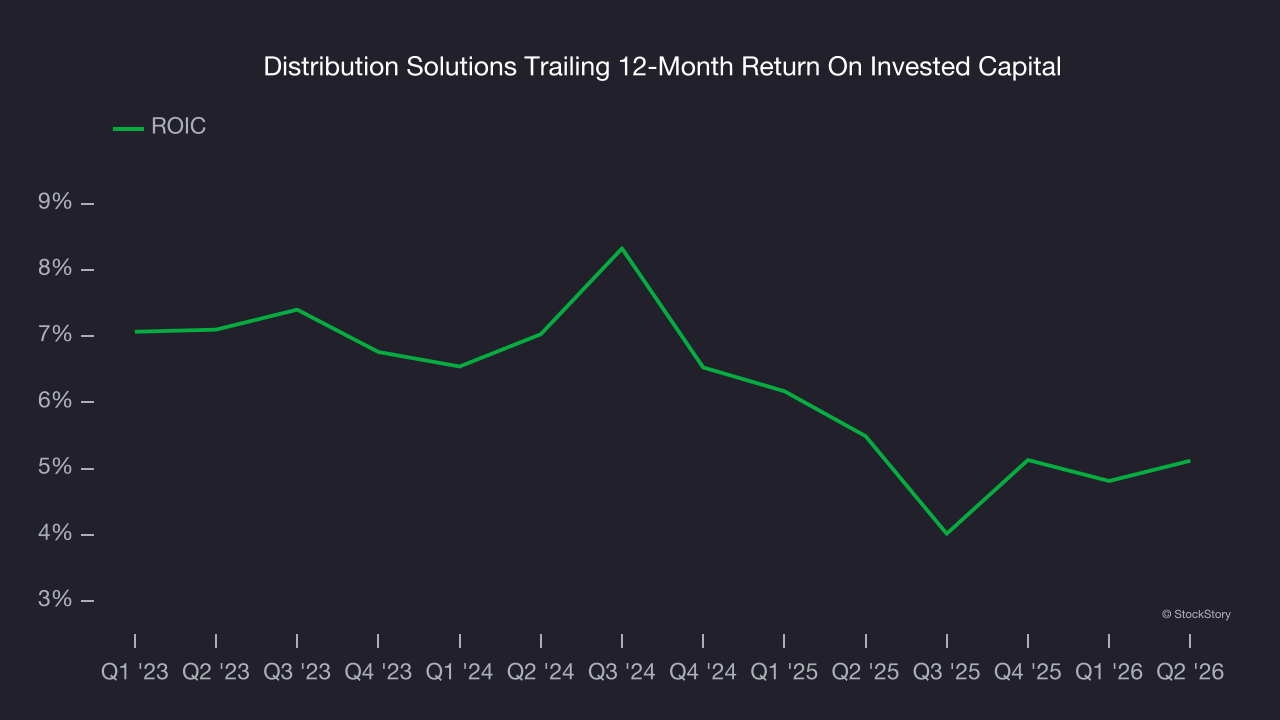
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Although Distribution Solutions has shown solid fundamentals lately, it historically did a mediocre job investing in profitable growth initiatives. Its four-year average ROIC was 6.2%, somewhat low compared to the best industrials companies that consistently pump out 20%+.
Final Judgment
Distribution Solutions has huge potential even though it has some open questions, and with its shares topping the market in recent months, the stock trades at 21.4× forward P/E (or $35.07 per share). Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.