

Altria has been treading water for the past six months, recording a small return of 3.3% while holding steady at $68.46. The stock also fell short of the S&P 500’s 17.5% gain during that period.
Is now the time to buy MO? Find out in our full research report, it’s free.
Why Does MO Stock Spark Debate?
Best known for its Marlboro brand of cigarettes, Altria (NYSE:MO) offers tobacco and nicotine products.
Two Positive Attributes:
1. Elite Gross Margin Powers Best-In-Class Business Model
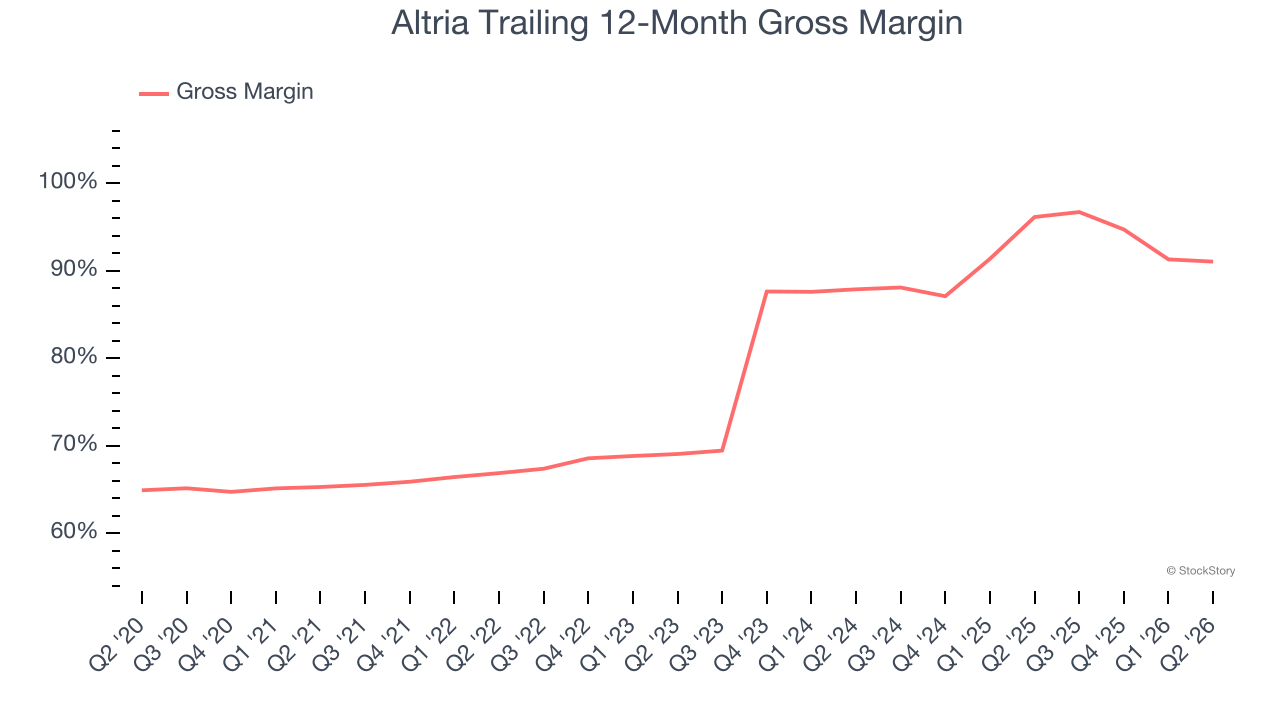
All else equal, we prefer higher gross margins because they usually indicate that a company sells more differentiated products, has a stronger brand, and commands pricing power.
Altria has best-in-class unit economics for a consumer staples company, enabling it to invest in areas such as marketing and talent to grow its brand. As you can see below, it averaged an elite 93.6% gross margin over the last two years. That means Altria only paid its suppliers $6.42 for every $100 in revenue.
2. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
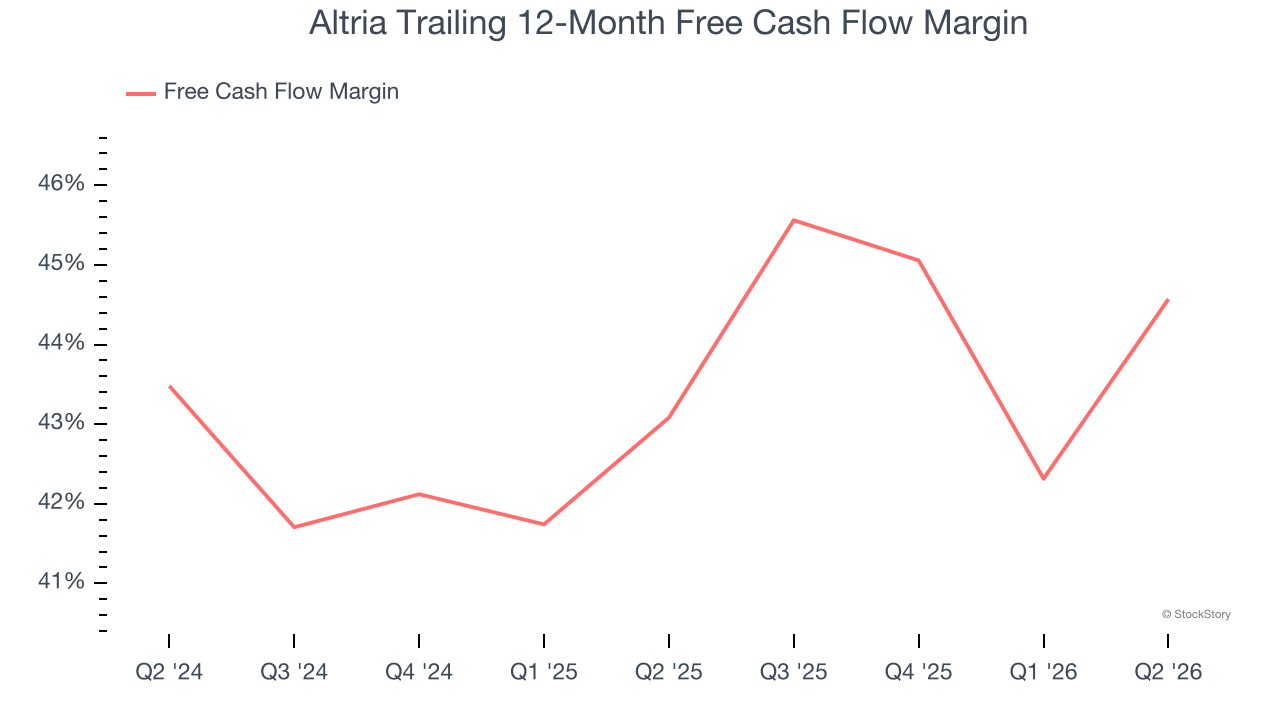
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Altria has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging an eye-popping 43.8% over the last two years.
One Reason to Be Careful:
Long-Term Revenue Growth Flatter Than a Pancake
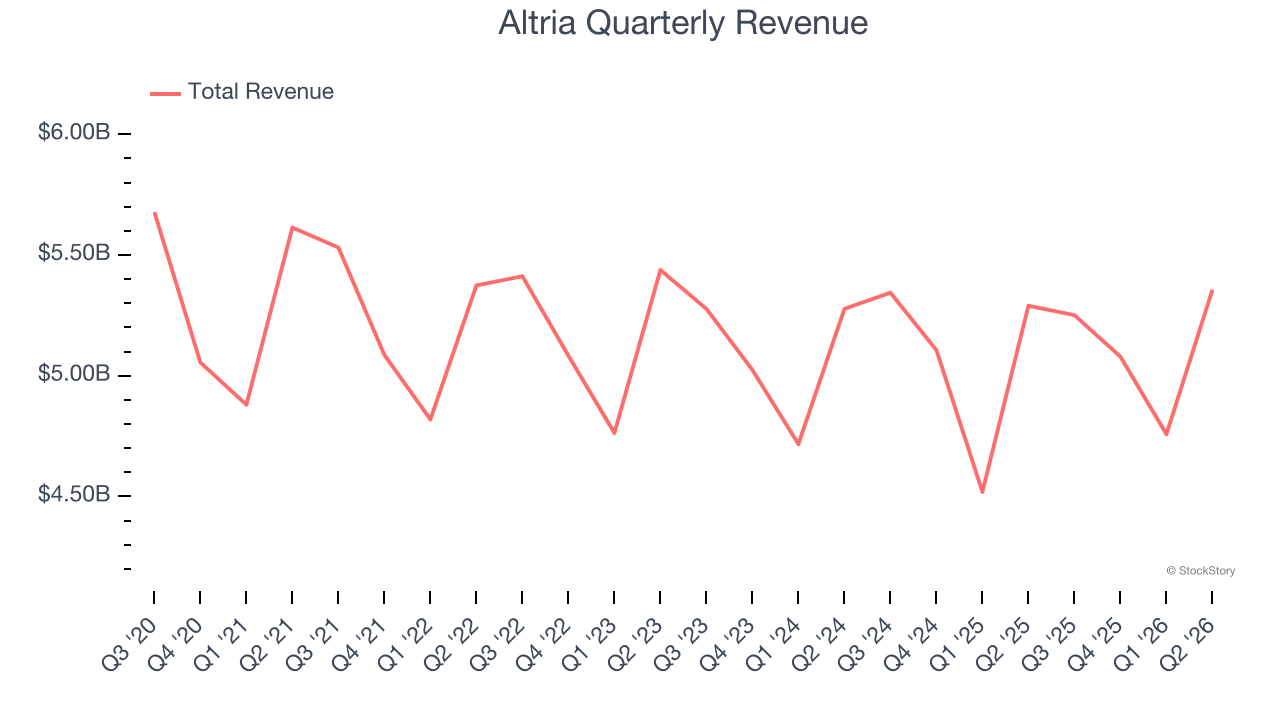
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, Altria struggled to consistently increase demand as its $20.44 billion of sales for the trailing 12 months was close to its revenue three years ago. This wasn’t a great result, but there are still things to like about Altria.
Final Judgment
Altria’s merits more than compensate for its flaws. With its shares trailing the market in recent months, the stock trades at 11.8× forward P/E (or $68.46 per share). Is now a good time to buy? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Altria
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.