
The past six months have been a windfall for Flex’s shareholders. The company’s stock price has jumped 78.7%, hitting $121.89 per share. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is now still a good time to buy FLEX? Or are investors being too optimistic? Find out in our full research report, it’s free.
Why Does FLEX Stock Spark Debate?
Originally known as Flextronics until its 2016 rebranding, Flex (NASDAQ:FLEX) is a global manufacturing partner that designs, engineers, and builds products for companies across industries from medical devices to solar trackers.
Two Positive Attributes:
1. Economies of Scale Give It Negotiating Leverage with Suppliers
With $29.27 billion in revenue over the past 12 months, Flex is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because it’s challenging to maintain high growth rates when you’ve already captured a large portion of the addressable market. To expand meaningfully, Flex likely needs to tweak its prices, innovate with new offerings, or enter new markets.
2. Outstanding Long-Term EPS Growth
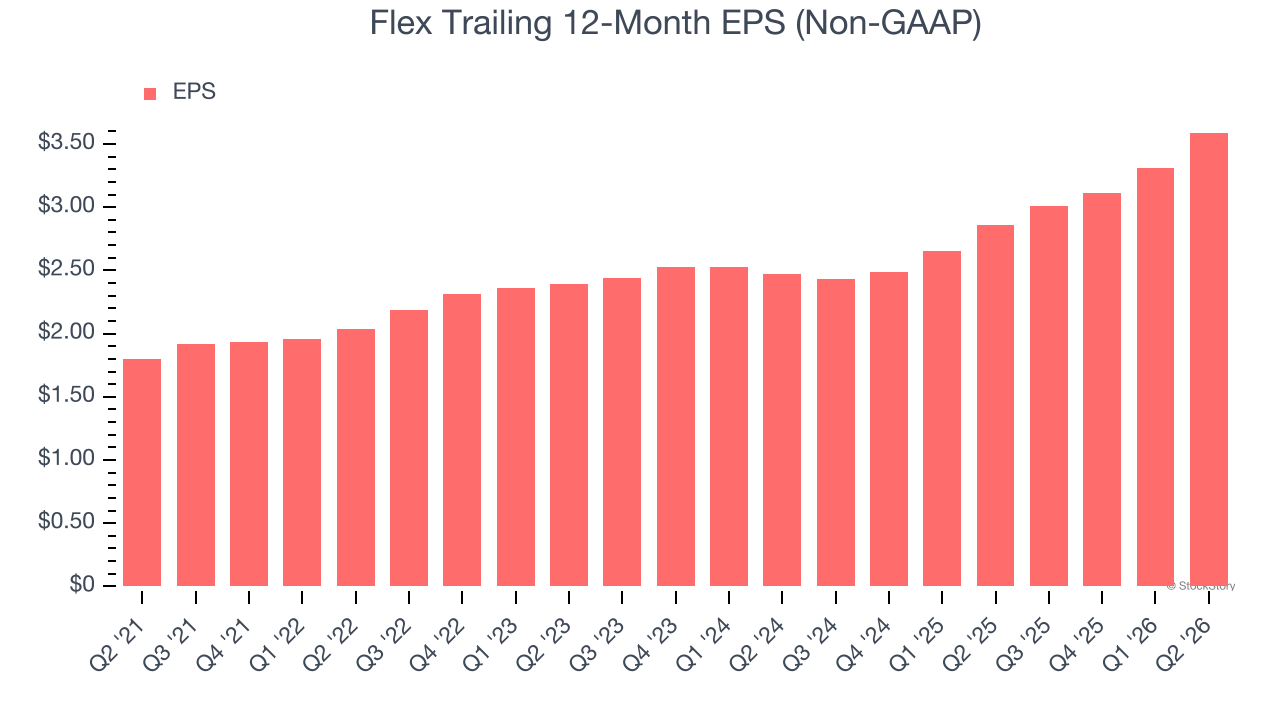
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Flex’s EPS grew at 14.8% compounded annual growth rate over the last five years, higher than its 2.9% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
One Reason to Be Careful:
Long-Term Revenue Growth Disappoints
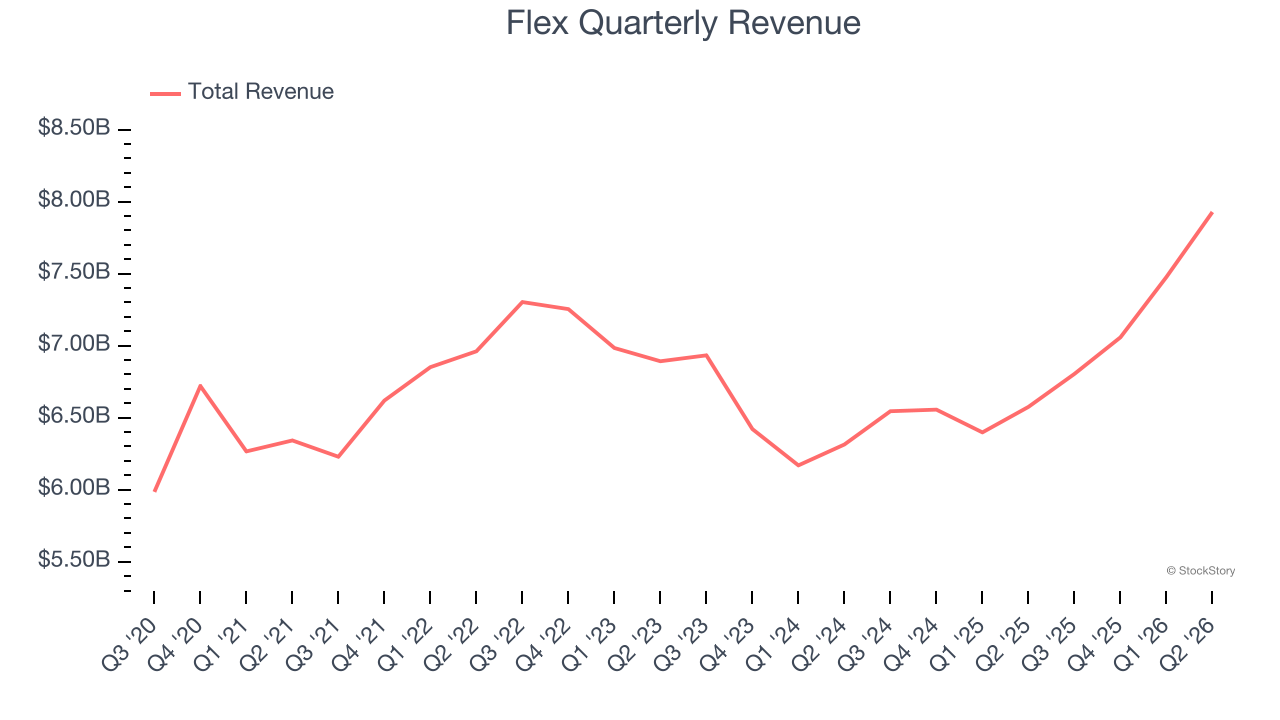
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Flex grew its sales at a sluggish 2.9% compounded annual growth rate. This wasn’t a great result, but there are still things to like about Flex.
Final Judgment
Flex’s merits more than compensate for its flaws, and with the recent rally, the stock trades at 22.4× forward P/E (or $121.89 per share). Is now a good time to buy despite the apparent froth? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than Flex
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.