
What a brutal six months it’s been for MasTec. The stock has dropped 34.7% and now trades at $220.31, rattling many shareholders. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Following the pullback, is this a buying opportunity for MTZ? Find out in our full research report, it’s free.
Why Is MasTec a Good Business?
Involved in the 1996 Olympic Games MasTec (NYSE:MTZ) is an infrastructure construction company that specializes in the telecommunications, energy, and utility industries.
1. Surging Backlog Locks In Future Sales
Investors interested in Engineering and Design Services companies should track backlog in addition to reported revenue. This metric shows the value of outstanding orders that have not yet been executed or delivered, giving visibility into MasTec’s future revenue streams.
MasTec’s backlog punched in at $21.39 billion in the latest quarter, and over the last two years, its year-on-year growth averaged 24.9%. This performance was fantastic and shows the company has a robust sales pipeline because it is accumulating more orders than it can fulfill. Its growth also suggests that customers are committing to MasTec for the long term, enhancing the business’s predictability. 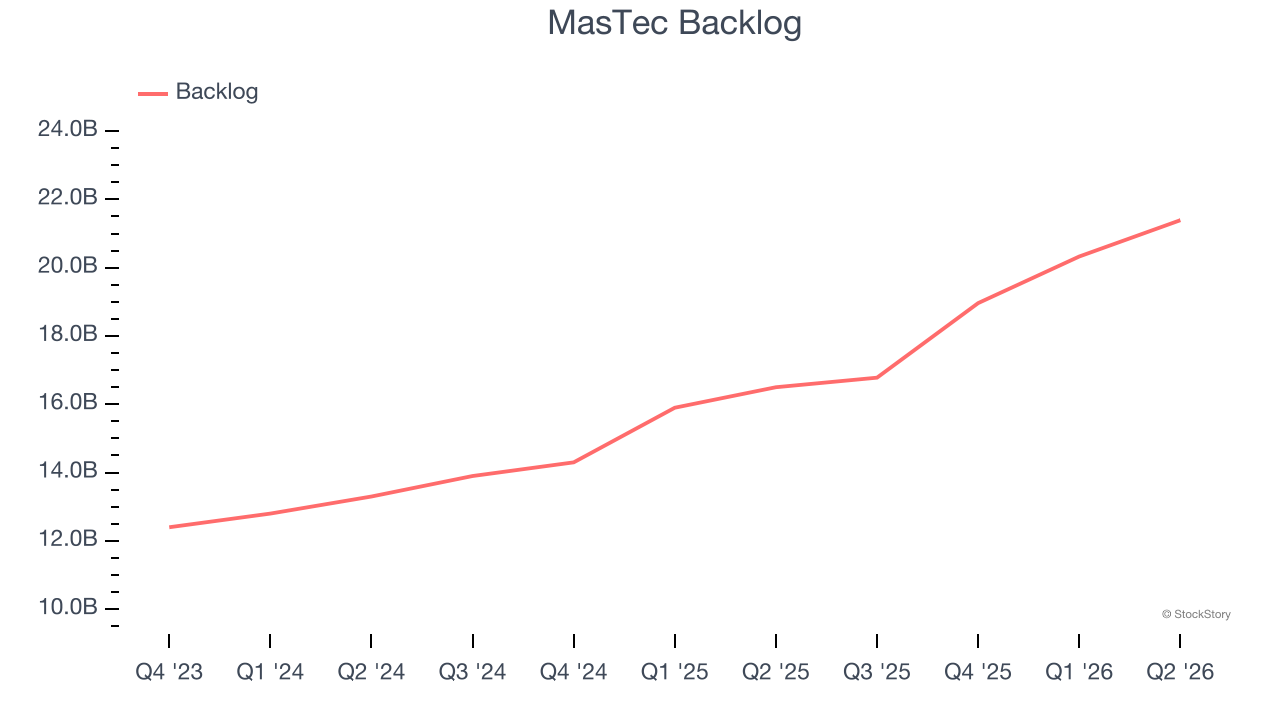
2. Projected Revenue Growth Is Remarkable
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite, though some deceleration is natural as businesses become larger.
Over the next 12 months, sell-side analysts expect MasTec’s revenue to rise by 24.8%, an improvement versus its 17.9% annualized growth for the past five years. This projection is eye-popping for a company of its scale and indicates its newer products and services will fuel better top-line performance.
3. EPS Surges Higher Over the Last Two Years
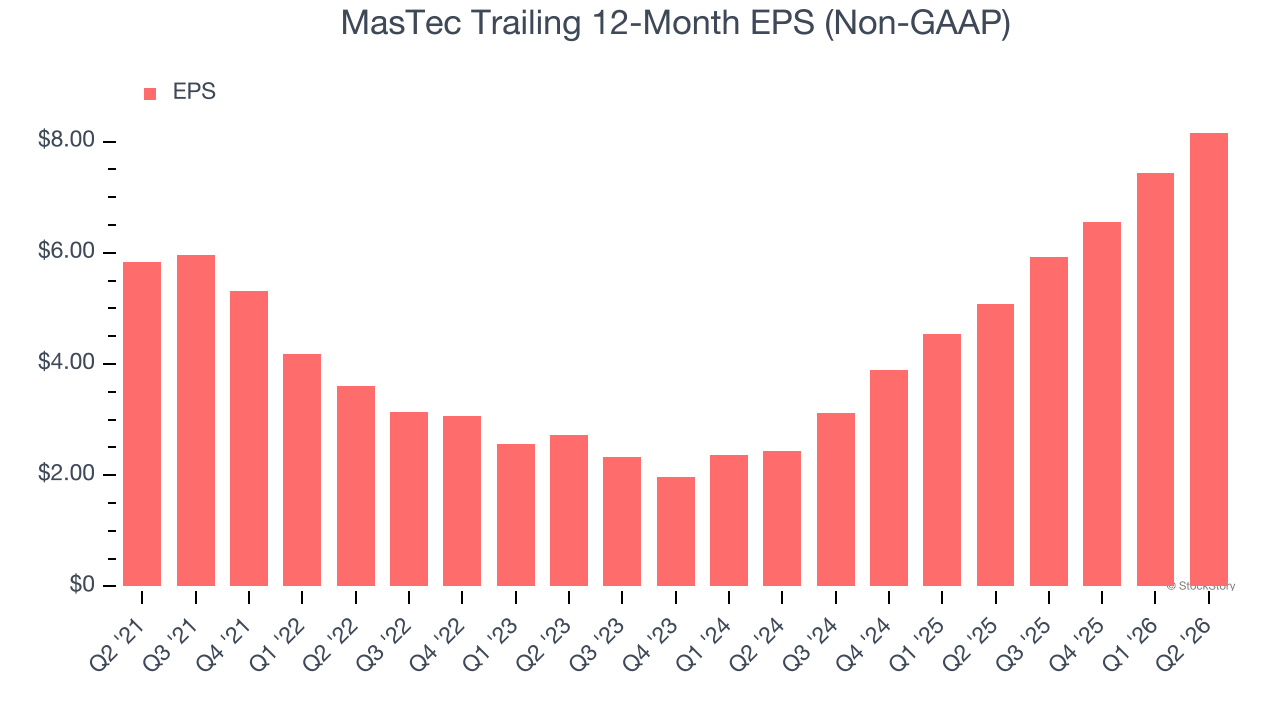
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
MasTec’s EPS grew at an astounding 82.9% compounded annual growth rate over the last two years, higher than its 15% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
Final Judgment
These are just a few reasons MasTec is a high-quality business worth owning. After the recent drawdown, the stock trades at 20× forward P/E (or $220.31 per share). Is now a good time to buy? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.