
While the S&P 500 is up 16.8% since April 2026, Performance Food Group (currently trading at $91.65 per share) has lagged behind, posting a return of 6.6%. This might have investors contemplating their next move.
Is there a buying opportunity in Performance Food Group, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Performance Food Group Will Underperform?
We’re cautious about Performance Food Group. Here are three reasons why PFGC doesn’t excite us, plus one stock we’d rather own.
1. Weak Sales Volumes Indicate Waning Demand
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Consumer Discretionary - Distributors company because there’s a ceiling to what customers will pay.
Over the last two years, Performance Food Group’s units sold averaged 6.9% year-on-year growth. This performance was underwhelming and suggests it might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 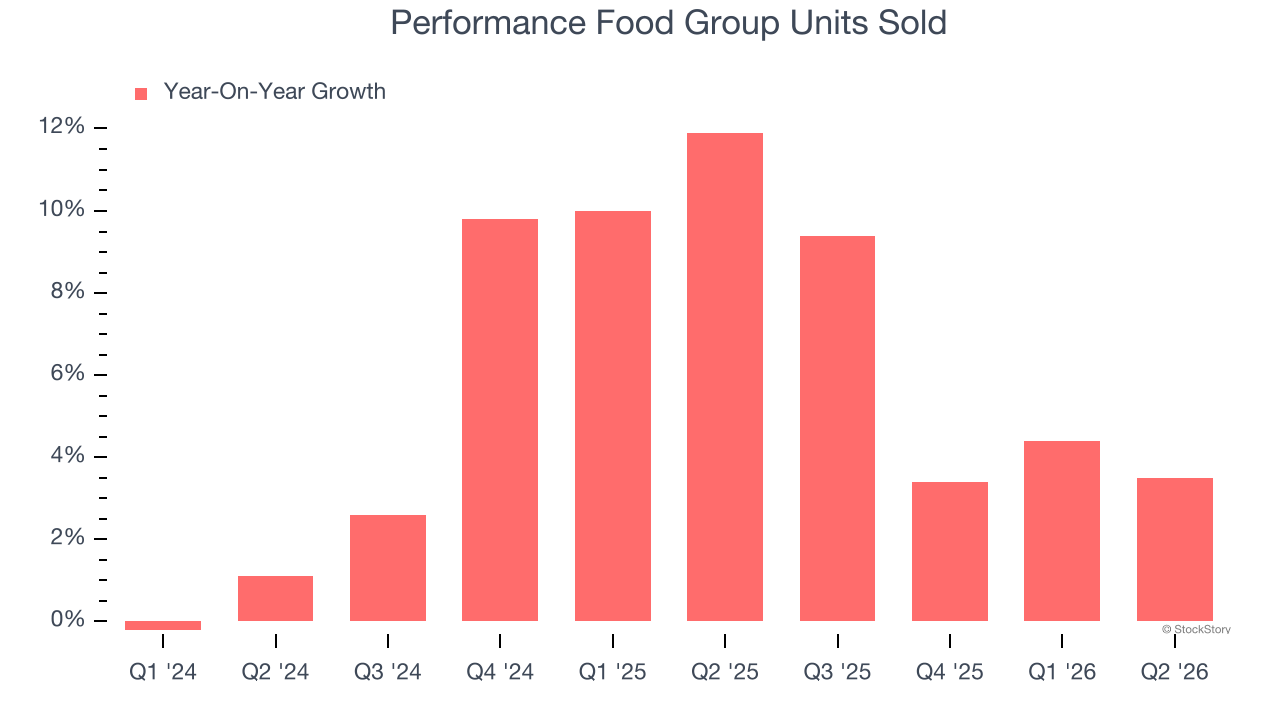
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
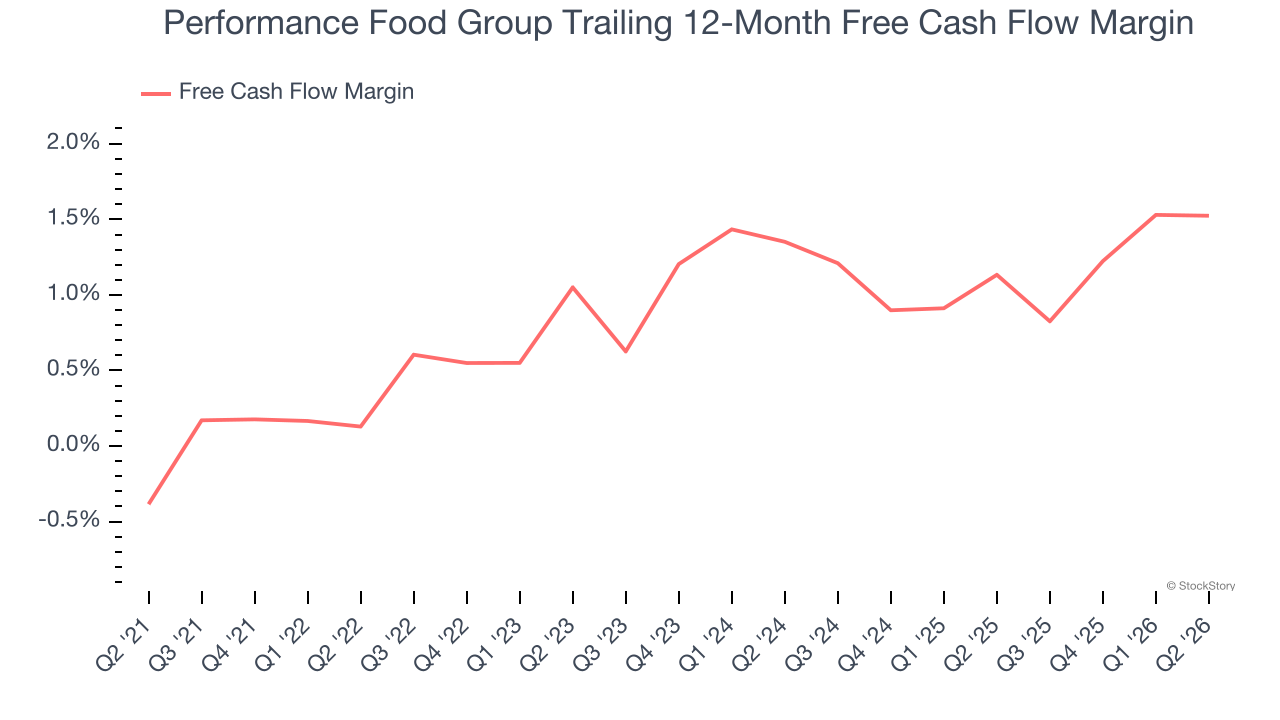
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Performance Food Group has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 1.3%, below what we’d expect for a consumer discretionary business.
3. New Investments Bear Fruit as ROIC Jumps
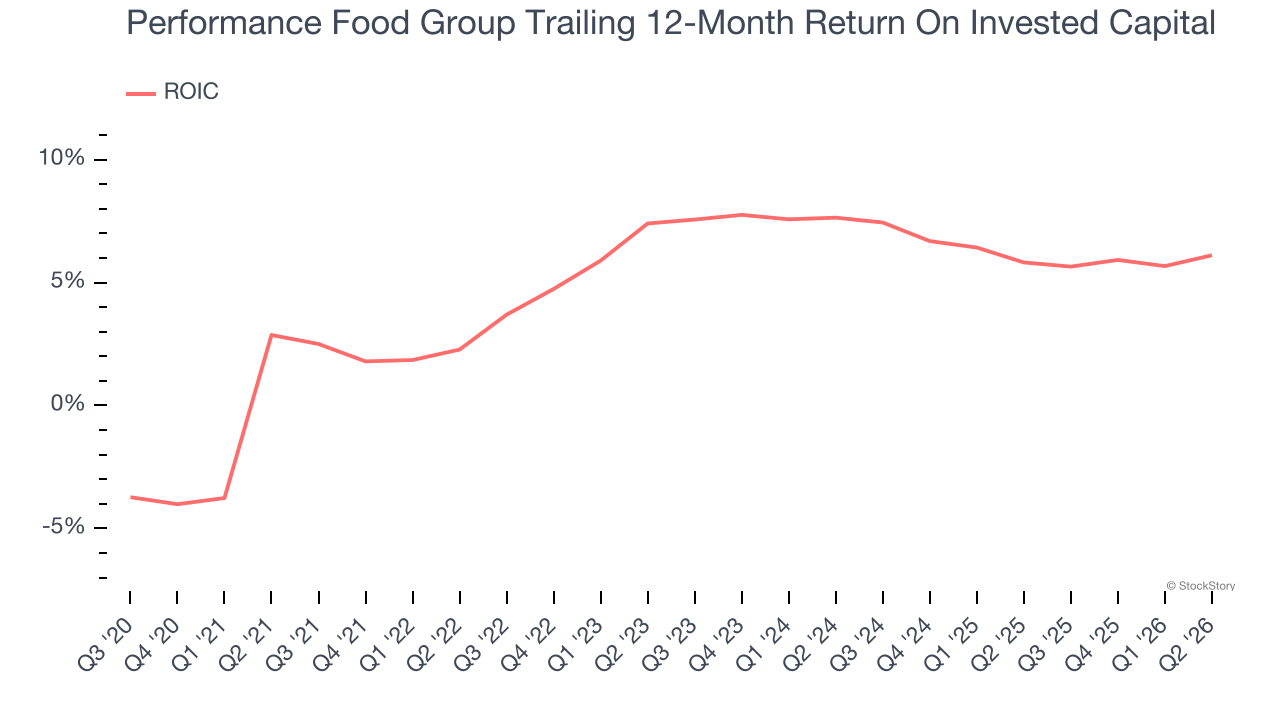
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
On average, Performance Food Group’s ROIC increased by 1.1 percentage points annually each year over the last few years. This is a good sign, and we hope the company can continue improving.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Performance Food Group, we’ll be cheering from the sidelines. With its shares trailing the market in recent months, the stock trades at 16.7× forward P/E (or $91.65 per share). At this valuation, there’s a lot of good news priced in - you can find more timely opportunities elsewhere. We’d suggest looking at one of Charlie Munger’s all-time favorite businesses.
Stocks We Like More Than Performance Food Group
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.