

Over the past six months, Airbnb has been a great trade, beating the S&P 500 by 12.9%. Its stock price has climbed to $164.43, representing a healthy 29.7% increase. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is it too late to buy ABNB? Find out in our full research report, it’s free.
Why Is ABNB a Good Business?
Founded by Brian Chesky and Joe Gebbia in their San Francisco apartment, Airbnb (NASDAQ:ABNB) is the world’s largest online marketplace for lodging, primarily homestays.
1. Nights and Experiences Booked Drive Additional Growth Opportunities
As an online travel company, Airbnb generates revenue growth by increasing both the number of stays (or experiences) booked and the commission charged on those bookings.
Over the last two years, Airbnb’s nights and experiences booked, a key performance metric for the company, increased by 9.3% annually to 148 million in the latest quarter. This growth rate is solid for a consumer internet business and indicates people are excited about its offerings. 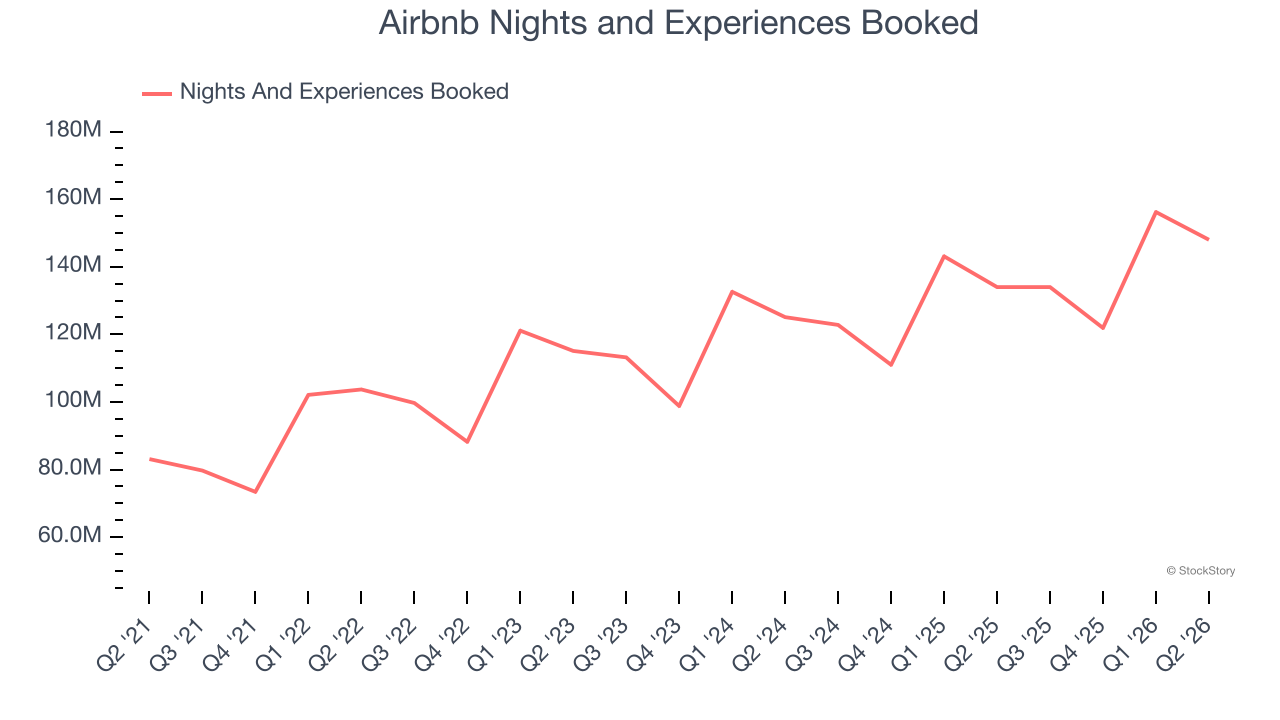
2. EBITDA Margin Reveals a Well-Run Organization
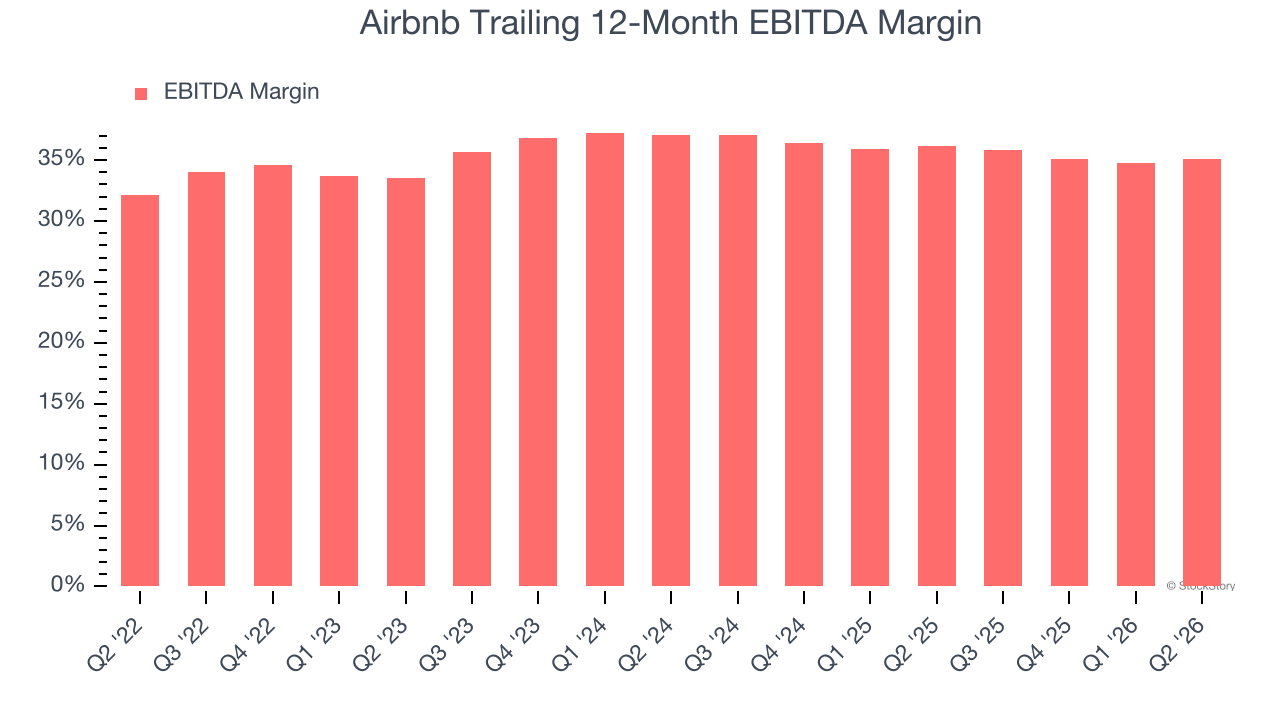
EBITDA is a good way of judging operating profitability for consumer internet companies because it excludes various one-time or non-cash expenses (depreciation), providing a more standardized view of the business’s profit potential.
Airbnb has been a well-oiled machine over the last two years. It demonstrated elite profitability for a consumer internet business, boasting an average EBITDA margin of 35.6%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
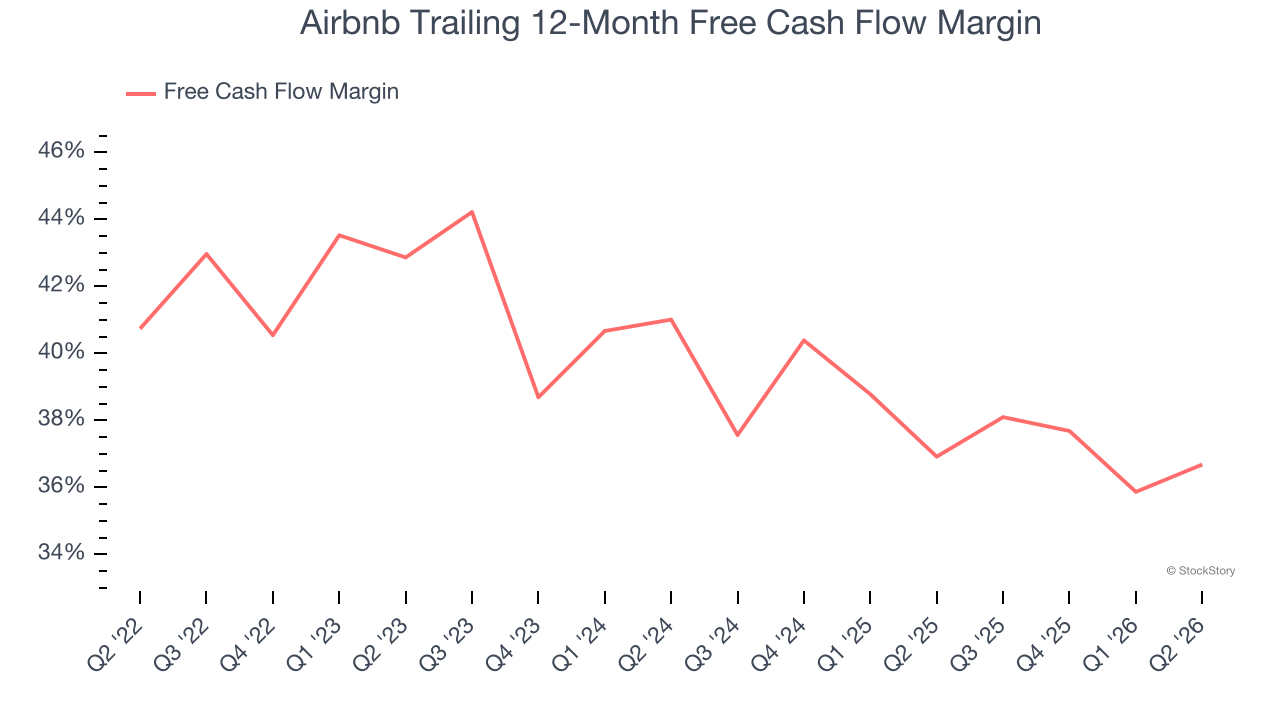
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Airbnb has shown terrific cash profitability, driven by its lucrative business model and cost-effective customer acquisition strategy that enable it to stay ahead of the competition through investments in new products rather than sales and marketing. The company’s free cash flow margin was among the best in the consumer internet sector, averaging an eye-popping 36.8% over the last two years.
Final Judgment
These are just a few reasons why we think Airbnb is a great business, and with its shares topping the market in recent months, the stock trades at 16.3× forward EV/EBITDA (or $164.43 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than Airbnb
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.