
Shareholders of The Trade Desk would probably like to forget the past six months even happened. The stock dropped 45.2% and now trades at $12.09. This was partly driven by its softer quarterly results and might have investors contemplating their next move.
Is now the time to buy The Trade Desk, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is The Trade Desk Not Exciting?
Even though the stock has become cheaper, we’re passing on The Trade Desk for now. Here are three reasons we avoid TTD, plus one stock we’d rather own.
1. Weak Billings Point to Soft Demand
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
The Trade Desk’s billings came in at $3.52 billion in Q2, and over the last four quarters, its year-on-year growth averaged 12.3%. This performance was underwhelming and suggests that increasing competition is causing challenges in acquiring/retaining customers. 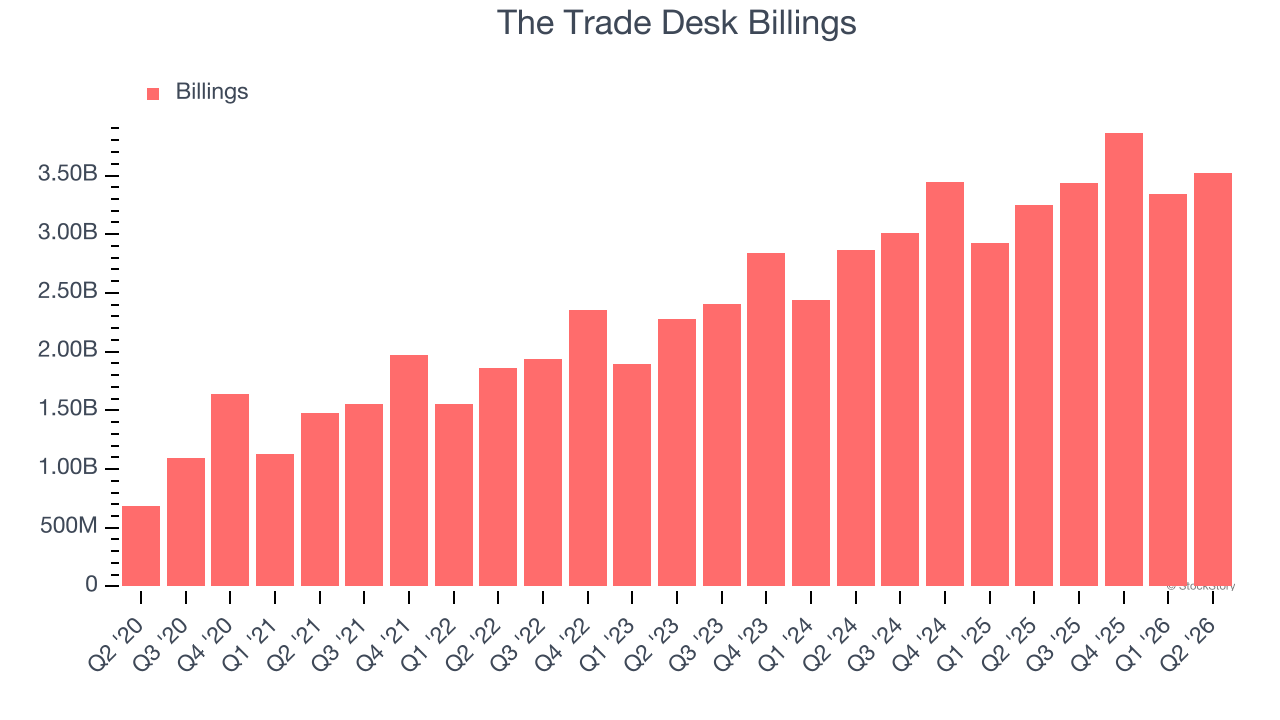
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect The Trade Desk’s revenue to drop by 14.7%, a decrease from its 23.6% annualized growth for the past five years. This projection doesn’t excite us and suggests its products and services will see some demand headwinds.
3. Cash Flow Margin Set to Decline
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Over the next year, analysts predict The Trade Desk’s cash conversion will fall. Their consensus estimates imply its free cash flow margin of 28.4% for the last 12 months will decrease to 18.2%.
Final Judgment
The Trade Desk isn’t a terrible business, but it isn’t one of our picks. Following the recent decline, the stock trades at 2.2× forward price-to-sales (or $12.09 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at one of our all-time favorite software stocks.
Stocks We Like More Than The Trade Desk
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.