

Wolverine Worldwide trades at $19.80 per share and has stayed right on track with the overall market, gaining 6.3% over the last six months. At the same time, the S&P 500 has returned 8.9%.
Is now the time to buy Wolverine Worldwide, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Wolverine Worldwide Will Underperform?
We don’t have much confidence in Wolverine Worldwide. Here are three reasons why there are better opportunities than WWW, plus one stock we’d rather own.
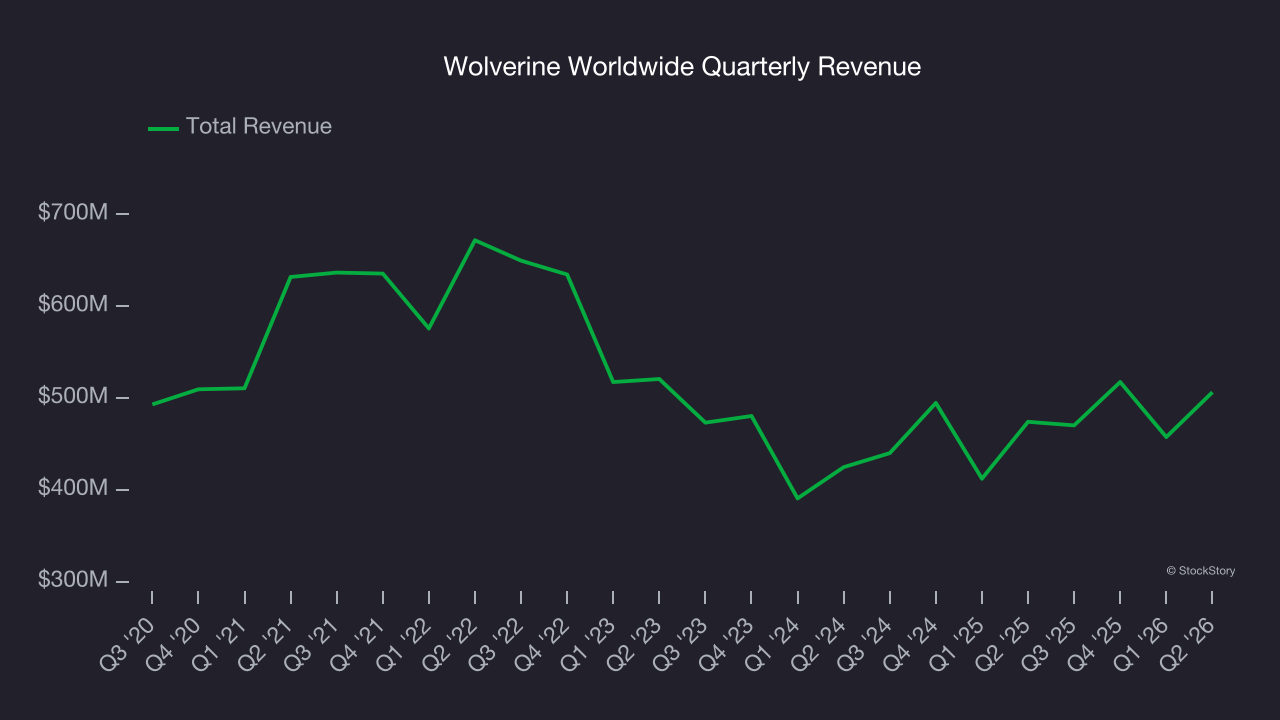
1. Revenue Spiraling Downwards
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Wolverine Worldwide’s demand was weak over the last five years as its sales fell at a 1.9% annual rate. This wasn’t a great result and is a sign of poor business quality.
2. EPS Trending Down
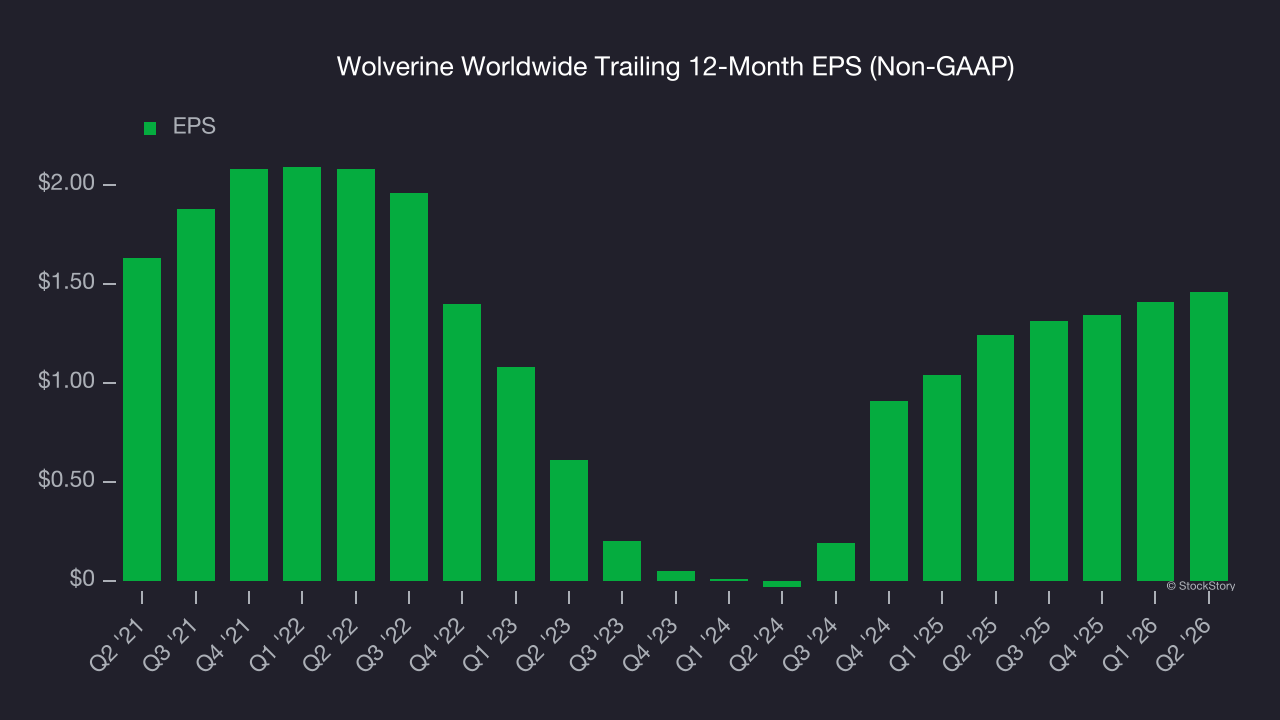
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Wolverine Worldwide, its EPS and revenue declined by 2.2% and 1.9% annually over the last five years. We tend to steer our readers away from companies with falling revenue and EPS, where diminishing earnings could imply changing secular trends and preferences. Consumer Discretionary companies are particularly exposed to this, and if the tide turns unexpectedly, Wolverine Worldwide’s low margin of safety could leave its stock price susceptible to large downswings.
3. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
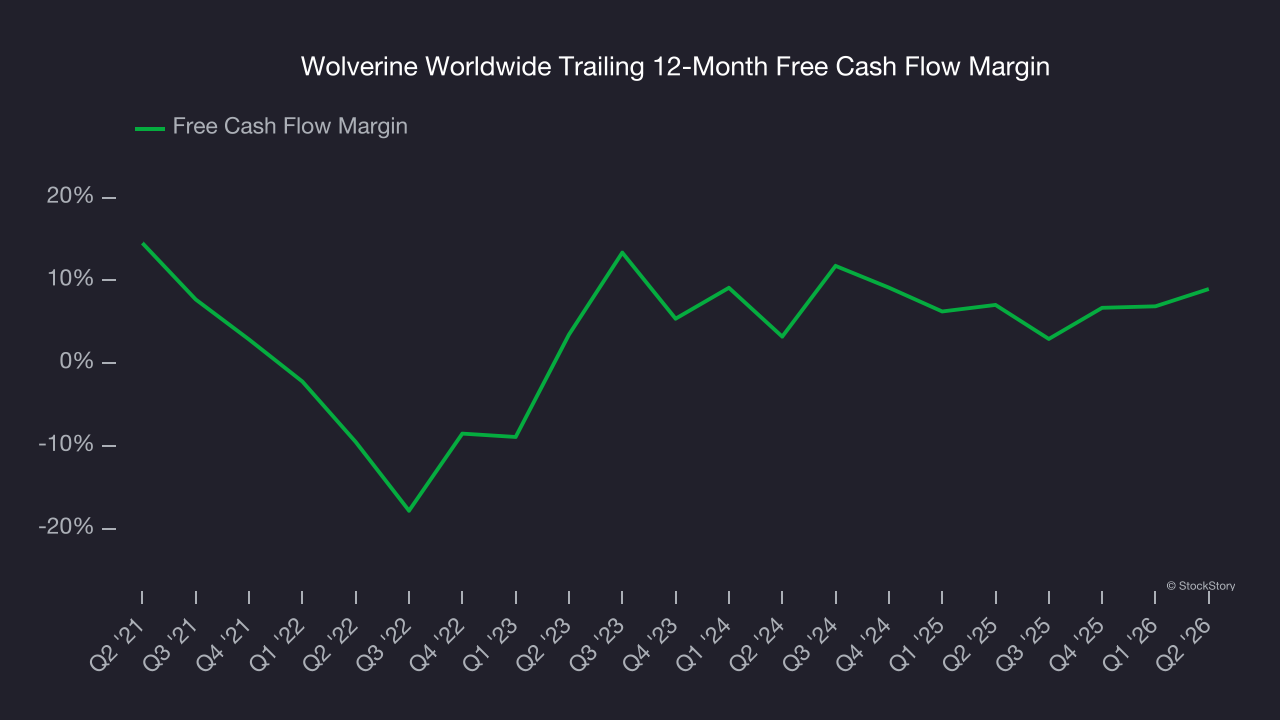
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Wolverine Worldwide has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 8%, below what we’d expect for a consumer discretionary business.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Wolverine Worldwide, we’ll be cheering from the sidelines. That said, the stock currently trades at 11.4× forward P/E (or $19.80 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are more exciting stocks to buy at the moment. We’d suggest looking at a top digital advertising platform riding the creator economy.
Stocks We Like More Than Wolverine Worldwide
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.