
Camden National Corporation trades at $55.85 and has moved in lockstep with the market. Its shares have returned 12.5% over the last six months while the S&P 500 has gained 9.7%.
Is there a buying opportunity in Camden National Corporation, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Camden National Corporation Not Exciting?
We don’t have much confidence in Camden National Corporation. Here are three reasons why CAC doesn’t excite us, plus one stock we’d rather own.
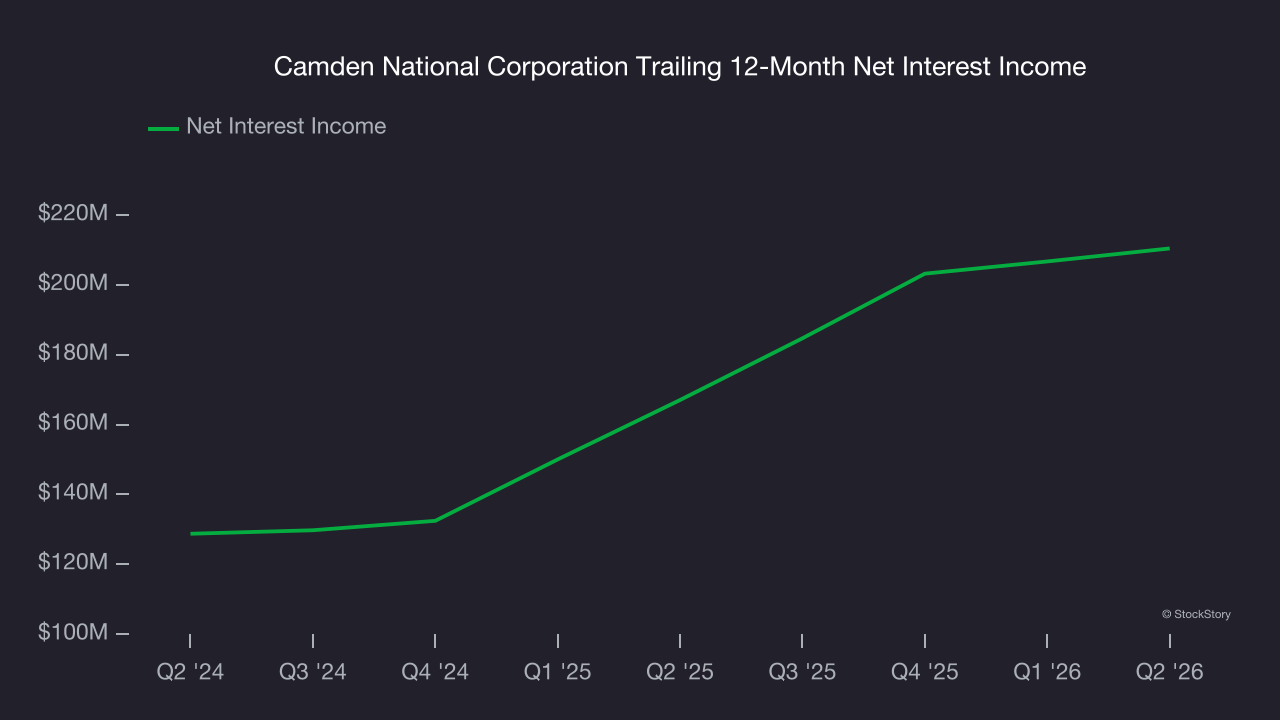
1. Net Interest Income Points to Soft Demand
Markets consistently prioritize net interest income over non-recurring fees, recognizing its superior quality compared to the more unpredictable revenue streams.
Camden National Corporation’s net interest income has grown at a 9.2% annualized rate over the last five years, slightly worse than the broader banking industry. Its growth was driven by both an increase in its outstanding loans and net interest margin, which represents how much a bank earns in relation to its outstanding loan book.
2. EPS Barely Growing
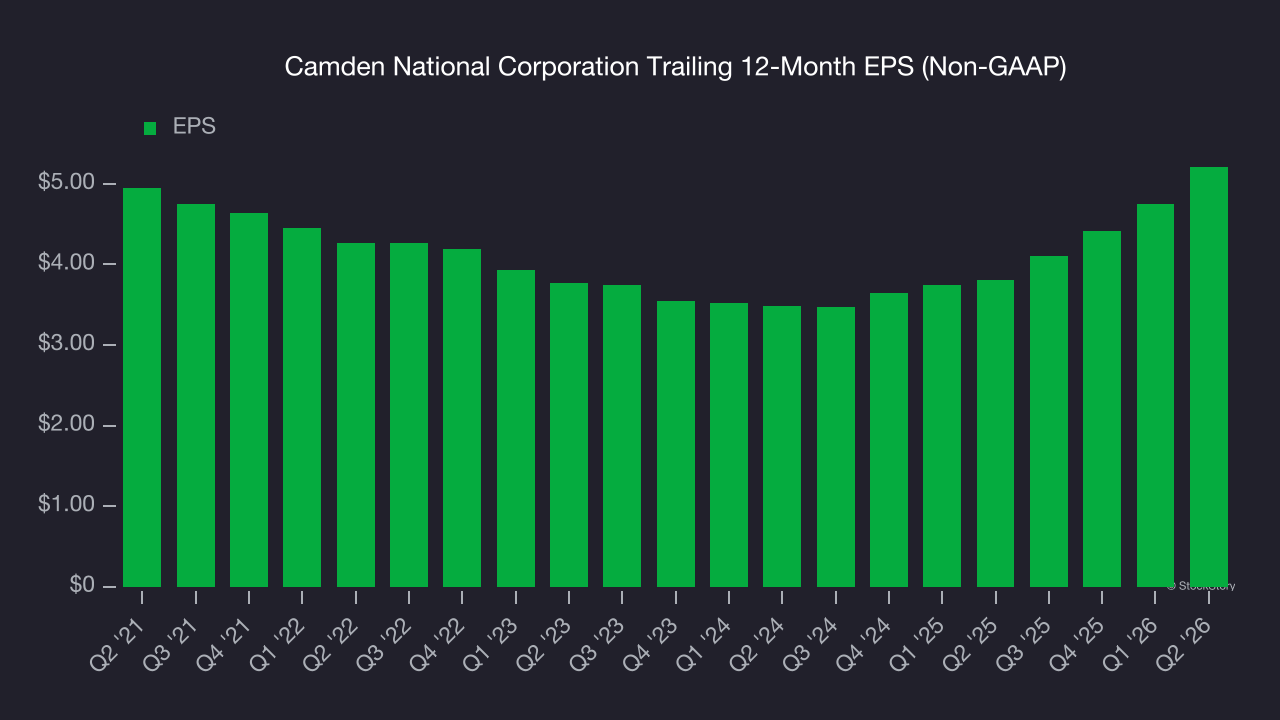
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Camden National Corporation’s EPS grew at a weak 1% compounded annual growth rate over the last five years, lower than its 6.9% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. Substandard TBVPS Growth Indicates Limited Asset Expansion
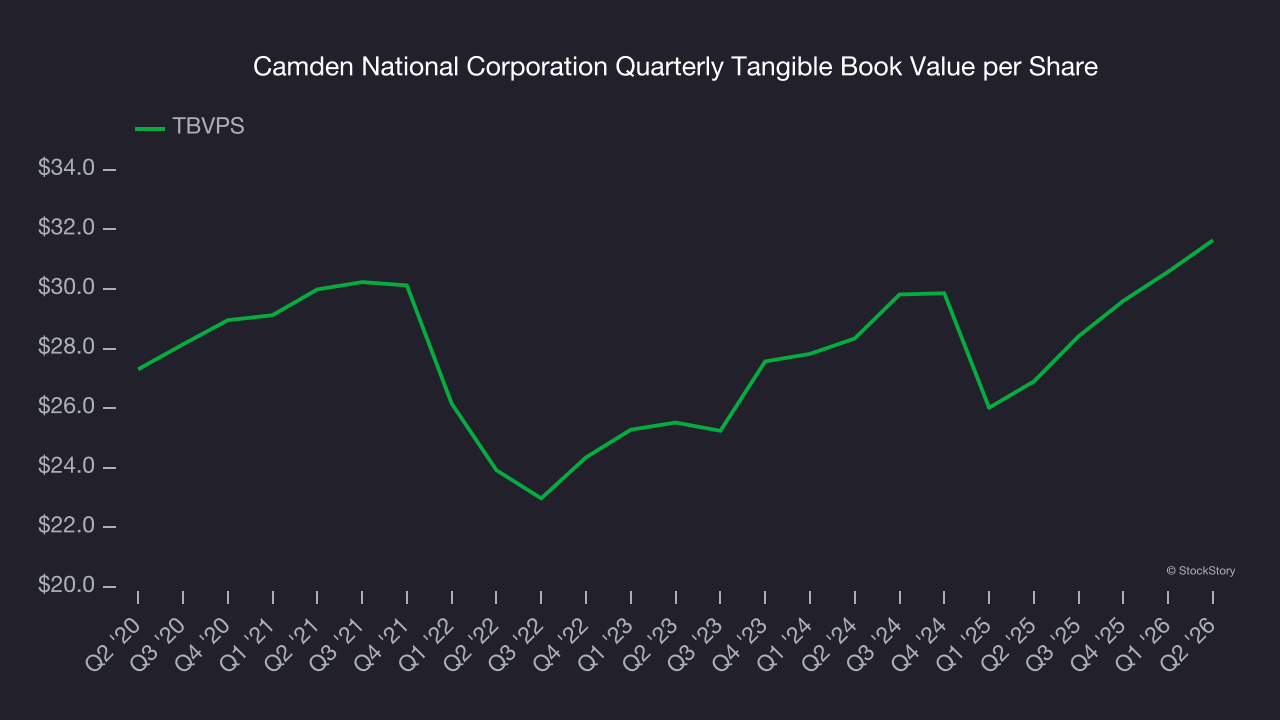
We consider tangible book value per share (TBVPS) the most important metric to track for banks. TBVPS represents the real, liquid net worth per share of a bank, excluding intangible assets that have debatable value upon liquidation.
Disappointingly for investors, Camden National Corporation’s TBVPS grew at a sluggish 5.7% annual clip over the last two years.
Final Judgment
Camden National Corporation isn’t a terrible business, but it isn’t one of our picks. That said, the stock currently trades at 1.2× forward P/B (or $55.85 per share). Investors with a higher risk tolerance might like the company, but we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at the most dominant software business in the world.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.