

Shareholders of Kratos would probably like to forget the past six months even happened. The stock dropped 45.2% and now trades at $40.78. This may have investors wondering how to approach the situation.
Following the drawdown, is now an opportune time to buy KTOS? Find out in our full research report, it’s free.
Why Is Kratos a Good Business?
Established with a commitment to supporting national security, Kratos (NASDAQ:KTOS) is a provider of advanced engineering, technology, and security solutions tailored for critical national security applications.
1. Core Business Firing on All Cylinders
Investors interested in Defense Contractors companies should track organic revenue in addition to reported revenue. This metric gives visibility into Kratos’s core business because it excludes one-time events such as mergers, acquisitions, and divestitures along with foreign currency fluctuations - non-fundamental factors that can manipulate the income statement.
Over the last two years, Kratos’s organic revenue averaged 14.9% year-on-year growth. This performance was fantastic and shows it can expand quickly without relying on expensive (and risky) acquisitions. 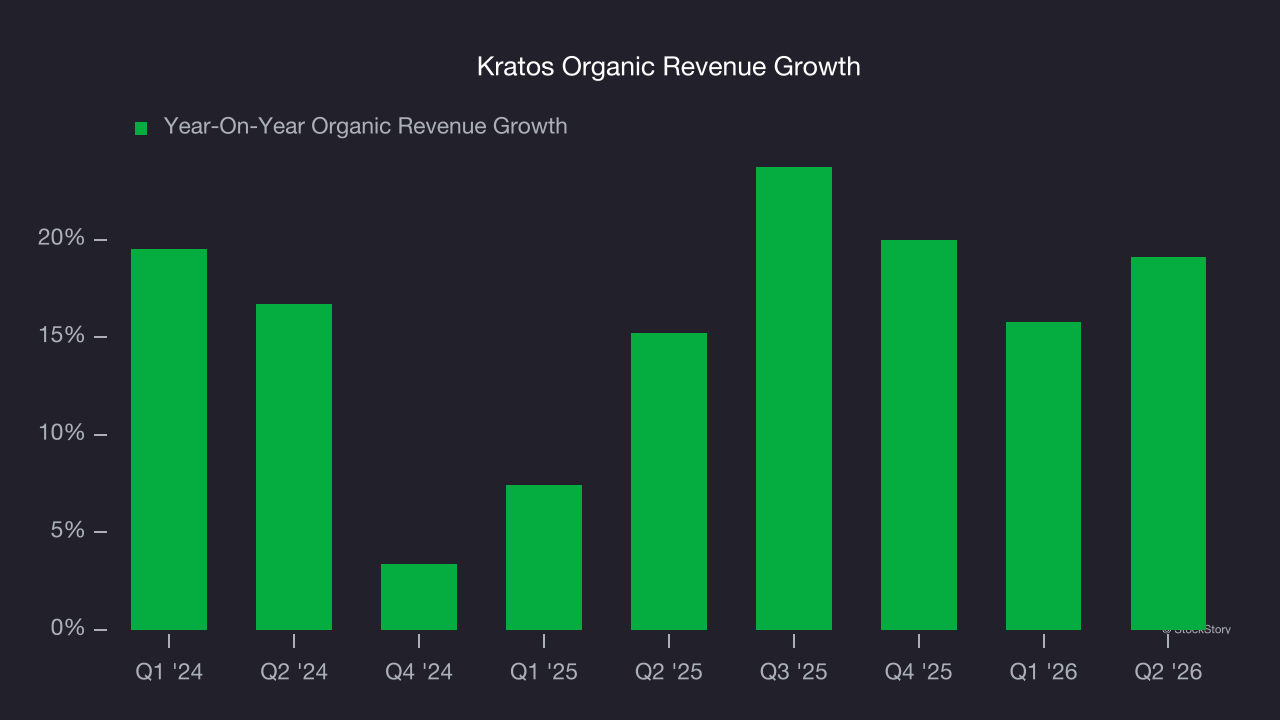
2. Projected Revenue Growth Is Remarkable
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite, though some deceleration is natural as businesses become larger.
Over the next 12 months, sell-side analysts expect Kratos’s revenue to rise by 30.6%, an improvement versus its 13.5% annualized growth for the past five years. This projection is eye-popping and suggests its newer products and services will spur better top-line performance.
3. Outstanding Long-Term EPS Growth
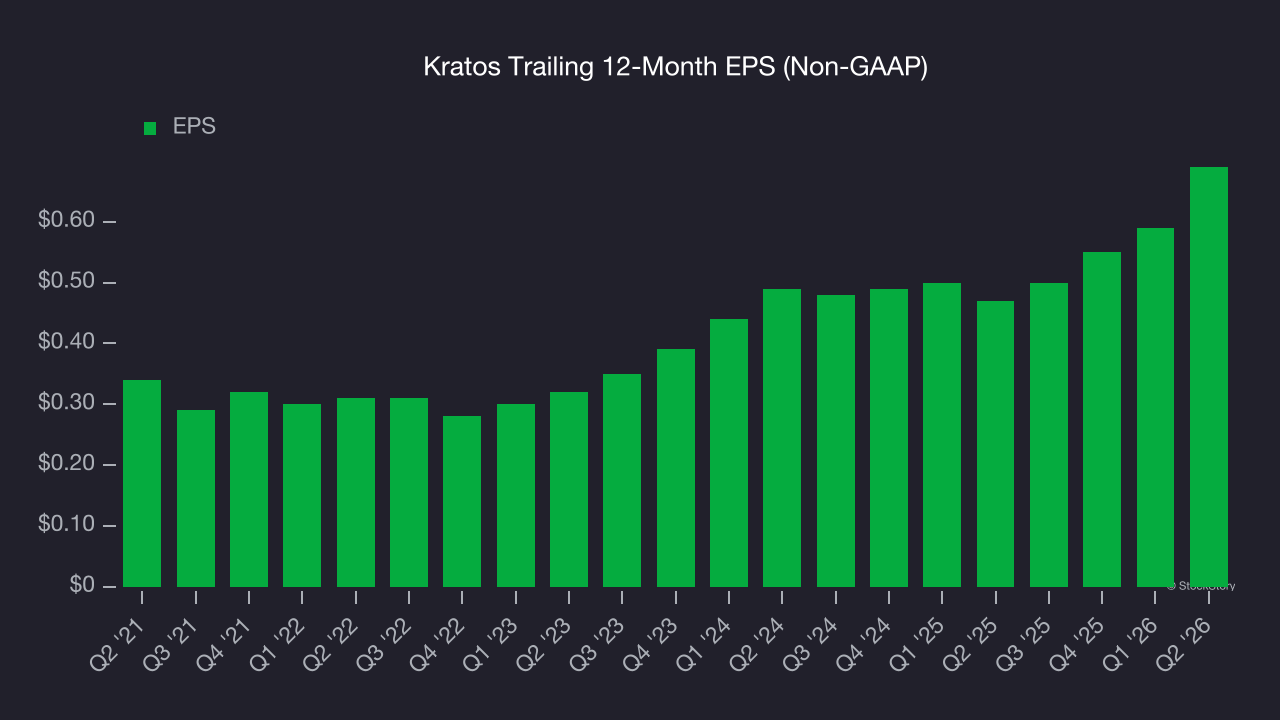
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Kratos’s spectacular 15.2% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
Final Judgment
These are just a few reasons Kratos is a high-quality business worth owning. With the recent decline, the stock trades at 42.8× forward P/E (or $40.78 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.