
Armstrong World currently trades at $166.57 per share and has shown little upside over the past six months, posting a small loss of 4%. The stock also fell short of the S&P 500’s 9.7% gain during that period.
Given the weaker price action, is now a good time to buy AWI? Or should investors expect a bumpy road ahead? Find out in our full research report, it’s free.
Why Is AWI a Good Business?
Started as a two-man shop dating back to the 1860s, Armstrong (NYSE:AWI) provides ceiling and wall products to commercial and residential spaces.
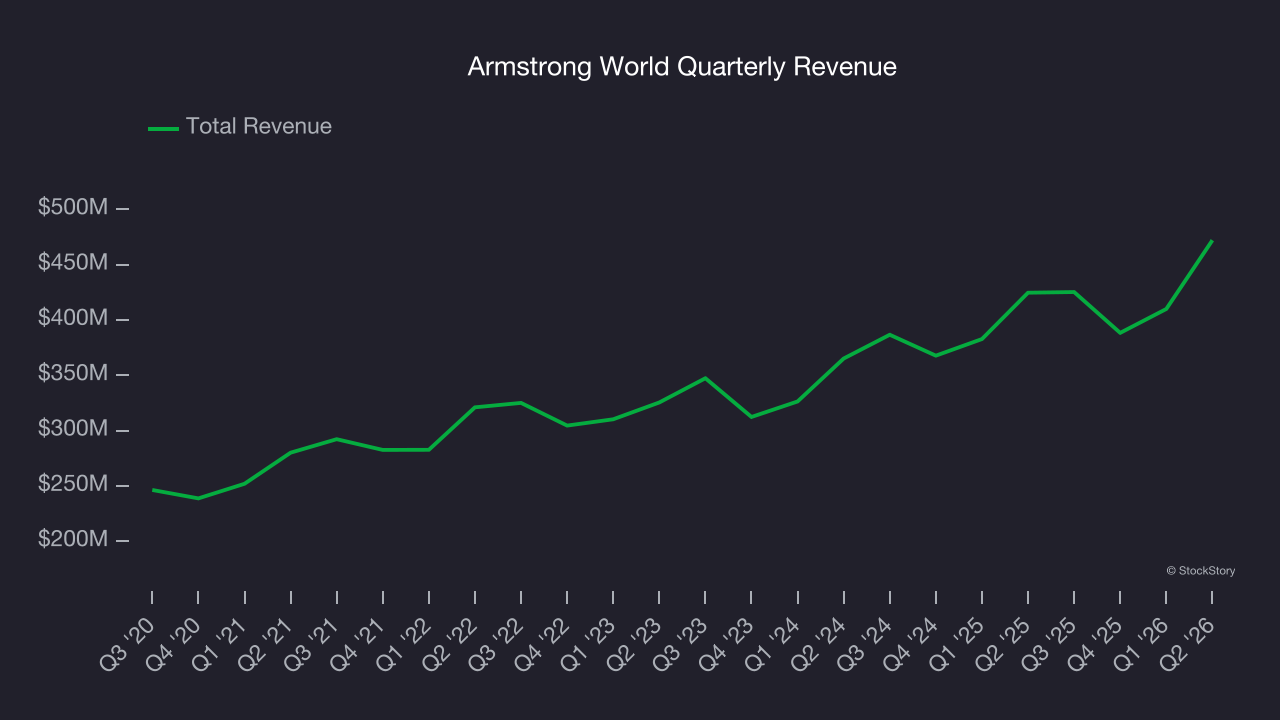
1. Skyrocketing Revenue Shows Strong Momentum
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Armstrong World grew its sales at an impressive 10.8% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers.
2. Operating Margin Reveals a Well-Run Organization
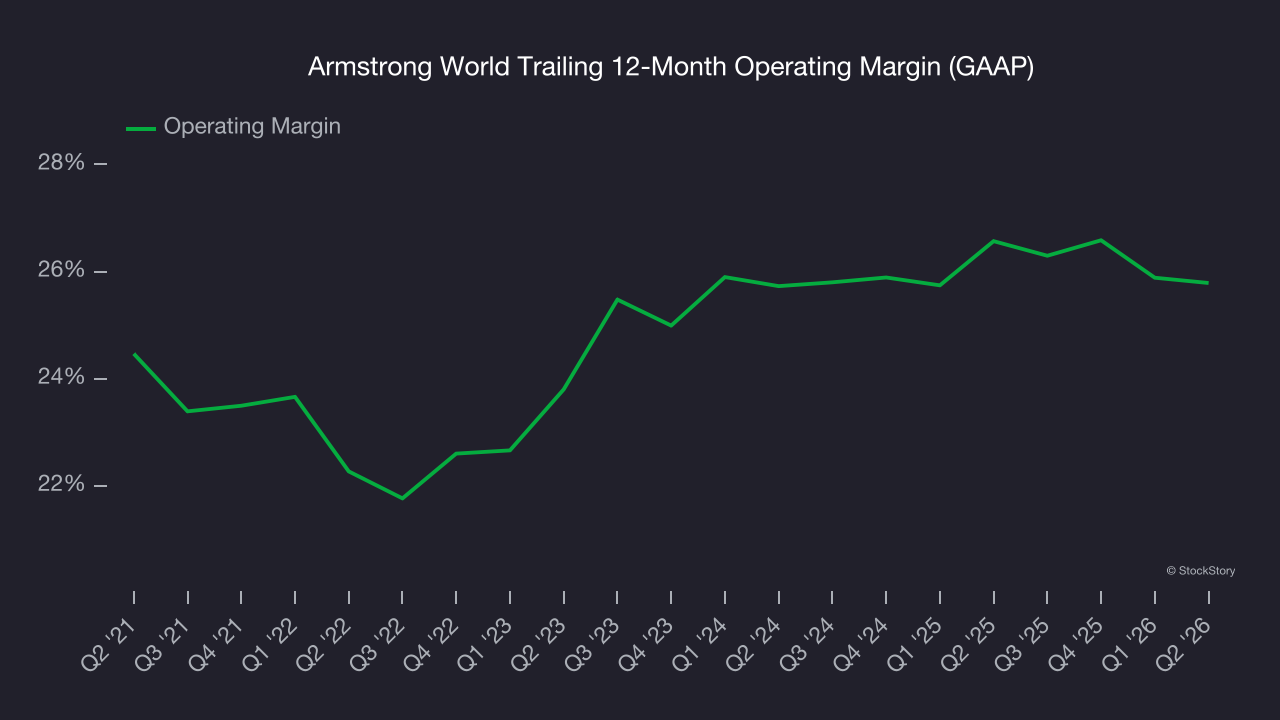
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
Armstrong World has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 25%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
3. Increasing Free Cash Flow Margin Juices Financials
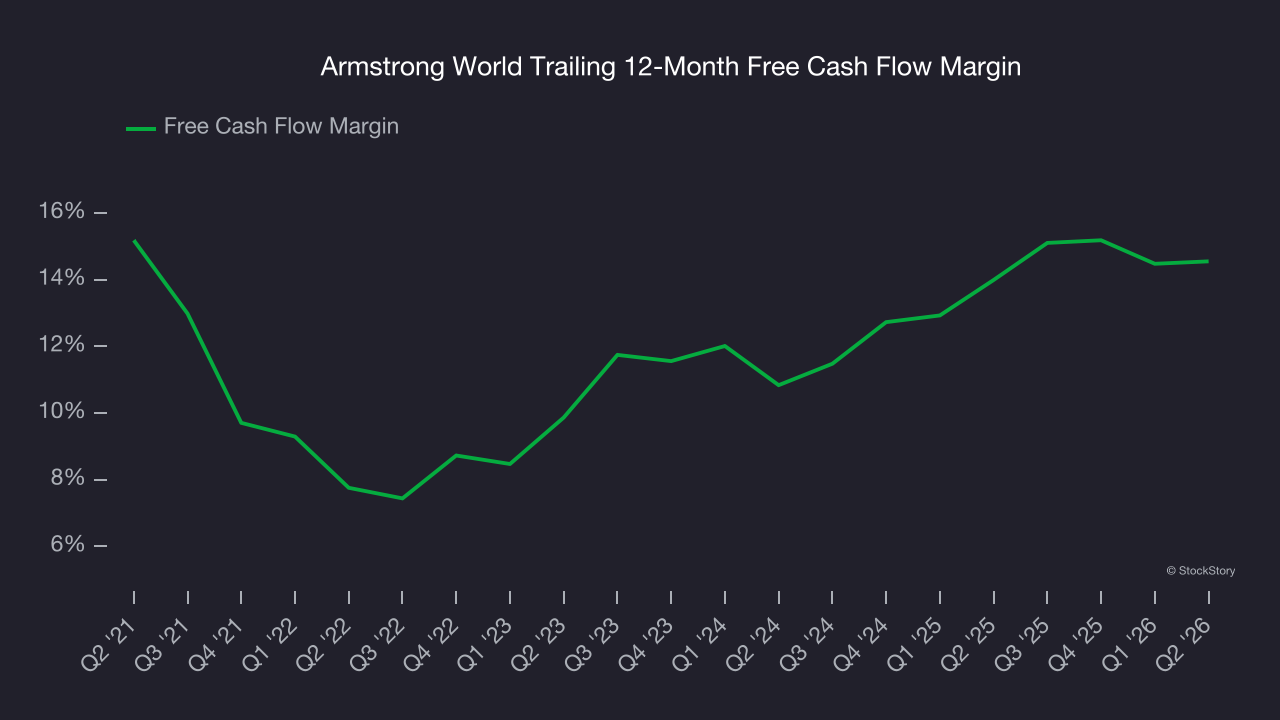
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
As you can see below, Armstrong World’s margin expanded by 6.8 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Armstrong World’s free cash flow margin for the trailing 12 months was 14.6%.
Final Judgment
These are just a few reasons why Armstrong World is a cream-of-the-crop industrials company. With its shares underperforming the market lately, the stock trades at 18.2× forward P/E (or $166.57 per share). Is now a good time to buy? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Armstrong World
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.