

Although Disney (currently trading at $108.21 per share) has gained 5.5% over the last six months, it has trailed the S&P 500’s 12% return during that period. This may have investors wondering how to approach the situation.
Is now the time to buy Disney, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Disney Will Underperform?
We’re passing on Disney for now. Here are three reasons we avoid DIS, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
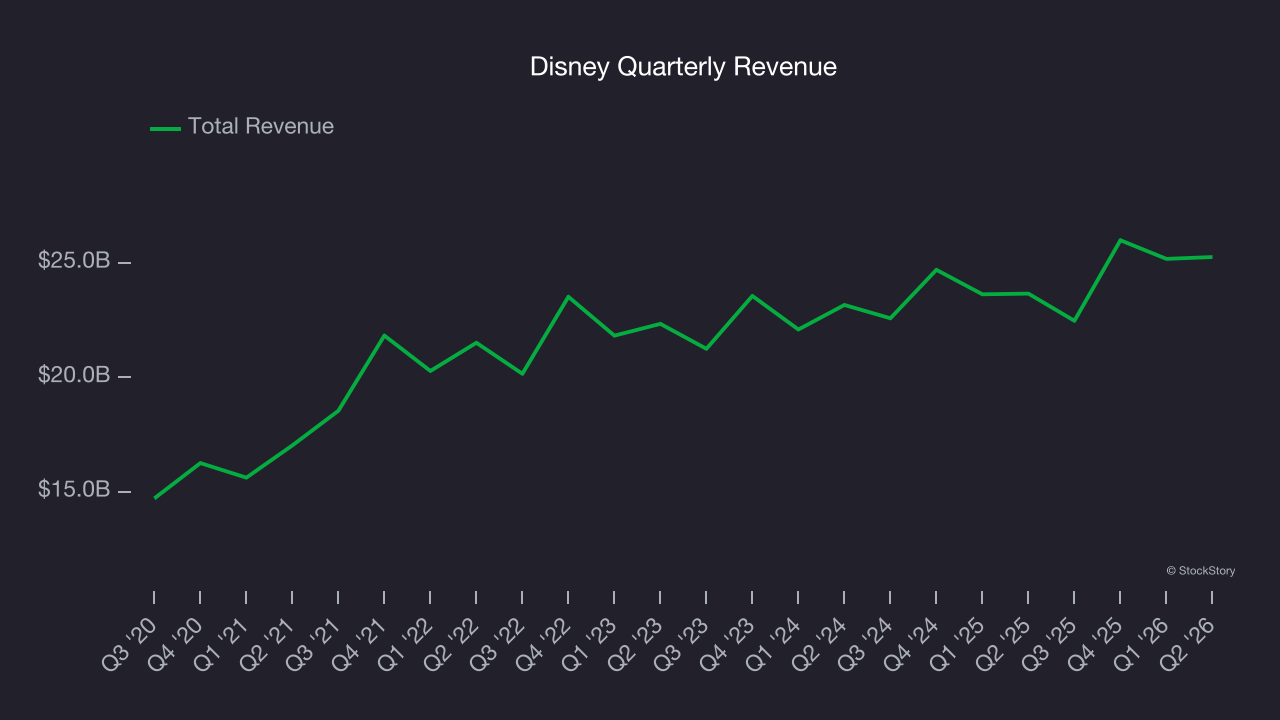
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Over the last five years, Disney grew its sales at a weak 9.2% compounded annual growth rate. This was below our standard for the consumer discretionary sector.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
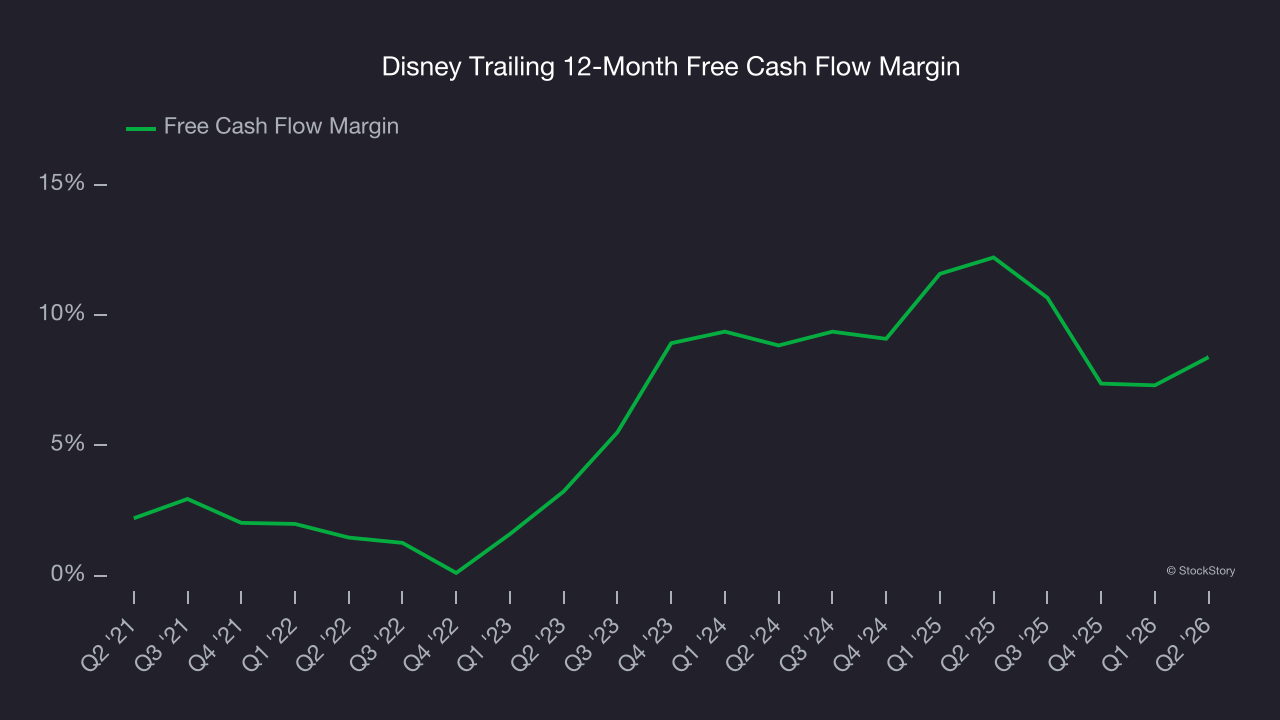
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Disney has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 10.3%, below what we’d expect for a consumer discretionary business.
3. Previous Growth Initiatives Haven’t Impressed
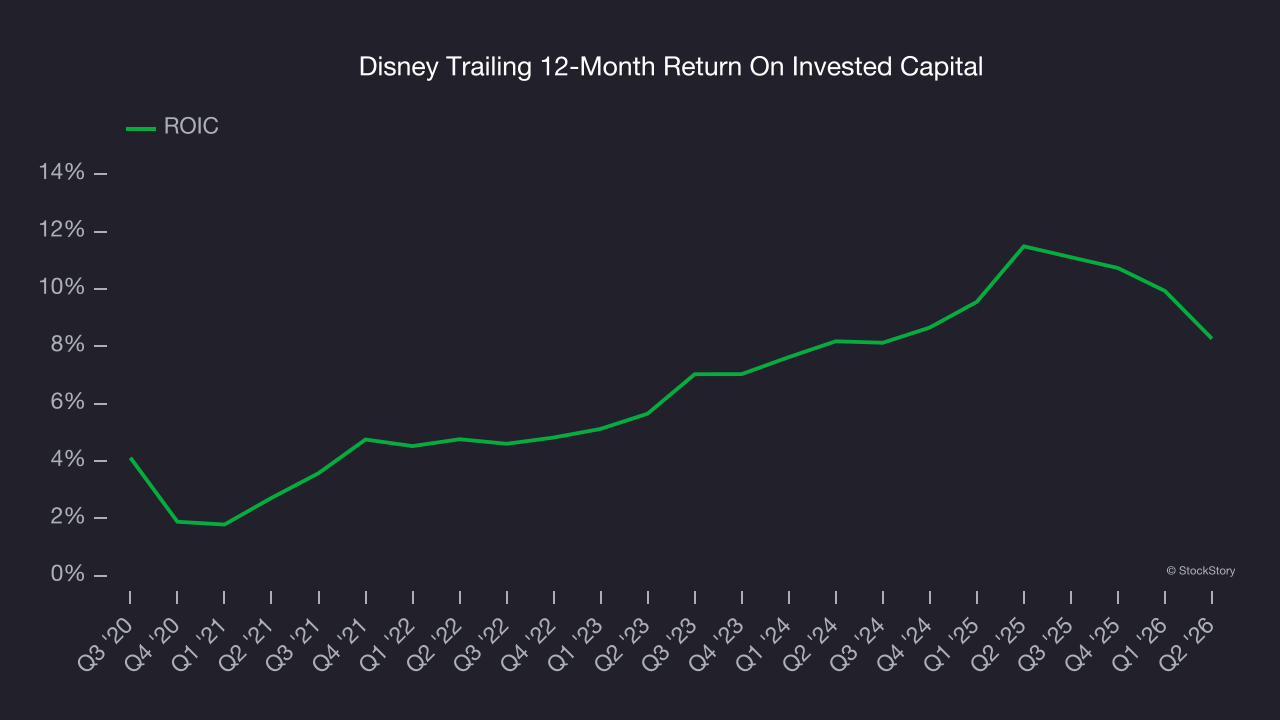
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Disney historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 7.7%, somewhat low compared to the best consumer discretionary companies that consistently pump out 65%+.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of Disney, we’ll be cheering from the sidelines. With its shares trailing the market in recent months, the stock trades at 14.4× forward P/E (or $108.21 per share). While this valuation is reasonable, we don’t see a big opportunity at the moment. There are superior stocks to buy right now. Let us point you toward our favorite semiconductor picks and shovels play.
Stocks We Like More Than Disney
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.