

The past six months have been a windfall for Best Buy’s shareholders. The company’s stock price has jumped 41.5%, hitting $87.79 per share. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Best Buy, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Best Buy Will Underperform?
We’re glad investors have benefited from the price increase, but we’re passing on Best Buy for now. Here are three reasons why BBY doesn’t excite us, plus one stock we’d rather own.
1. Stores Are Closing, a Headwind for Revenue
A retailer’s store count influences how much it can sell and how quickly revenue can grow.
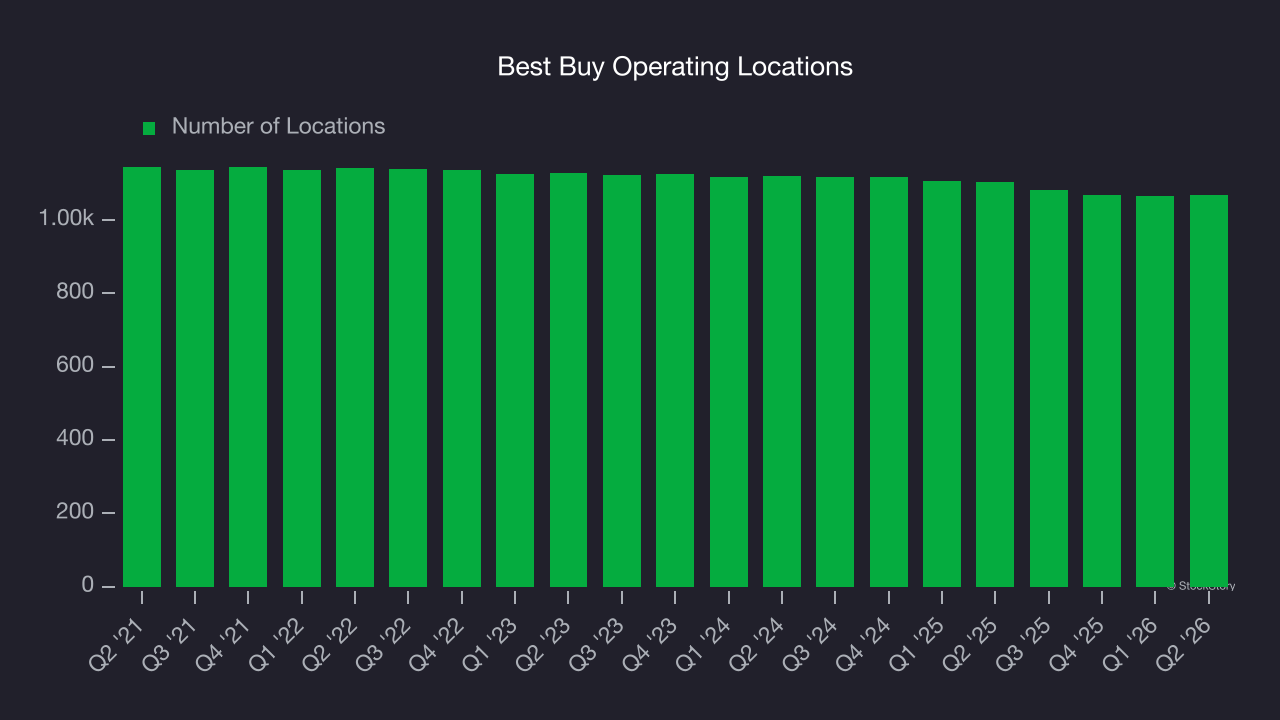
Best Buy operated 1,068 locations in the latest quarter. Over the last two years, the company has generally closed its stores, averaging 2.3% annual declines.
When a retailer shutters stores, it usually means that brick-and-mortar demand is less than supply, and it is responding by closing underperforming locations to improve profitability.
2. Flat Same-Store Sales Indicate Weak Demand
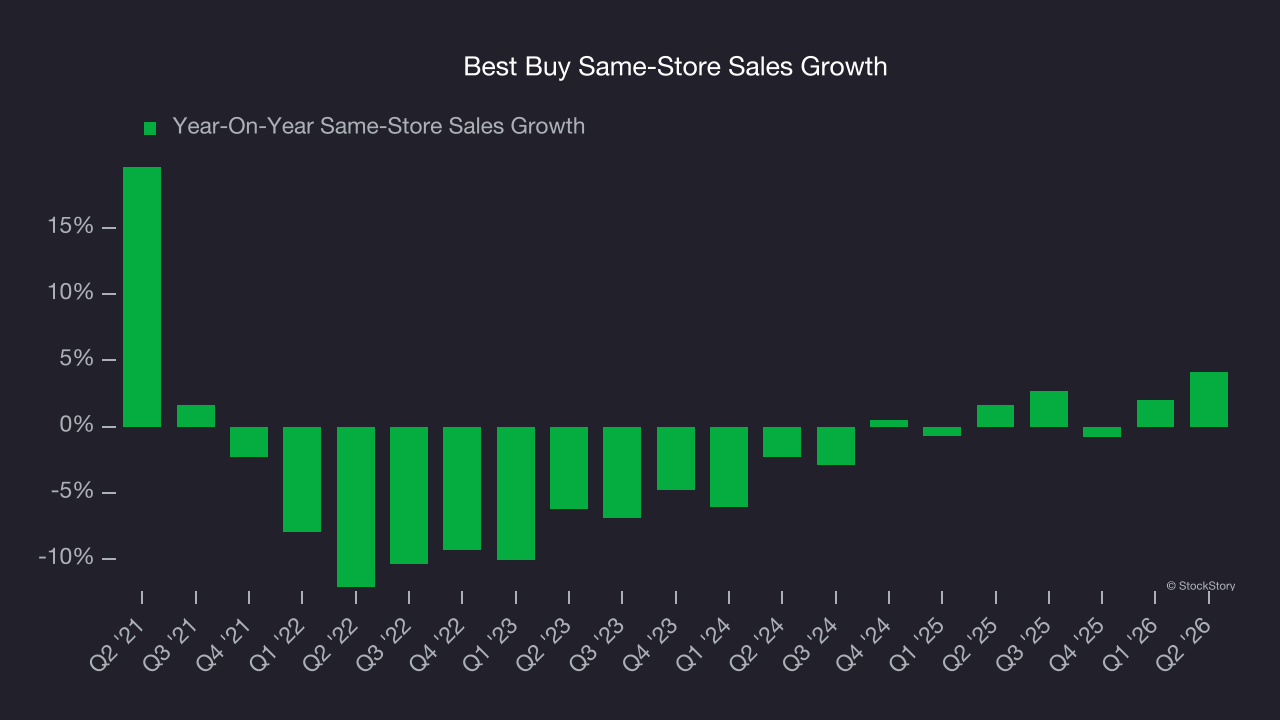
Same-store sales is a key performance indicator used to measure organic growth at brick-and-mortar shops for at least a year.
Best Buy’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat.
3. Low Gross Margin Reveals Weak Structural Profitability
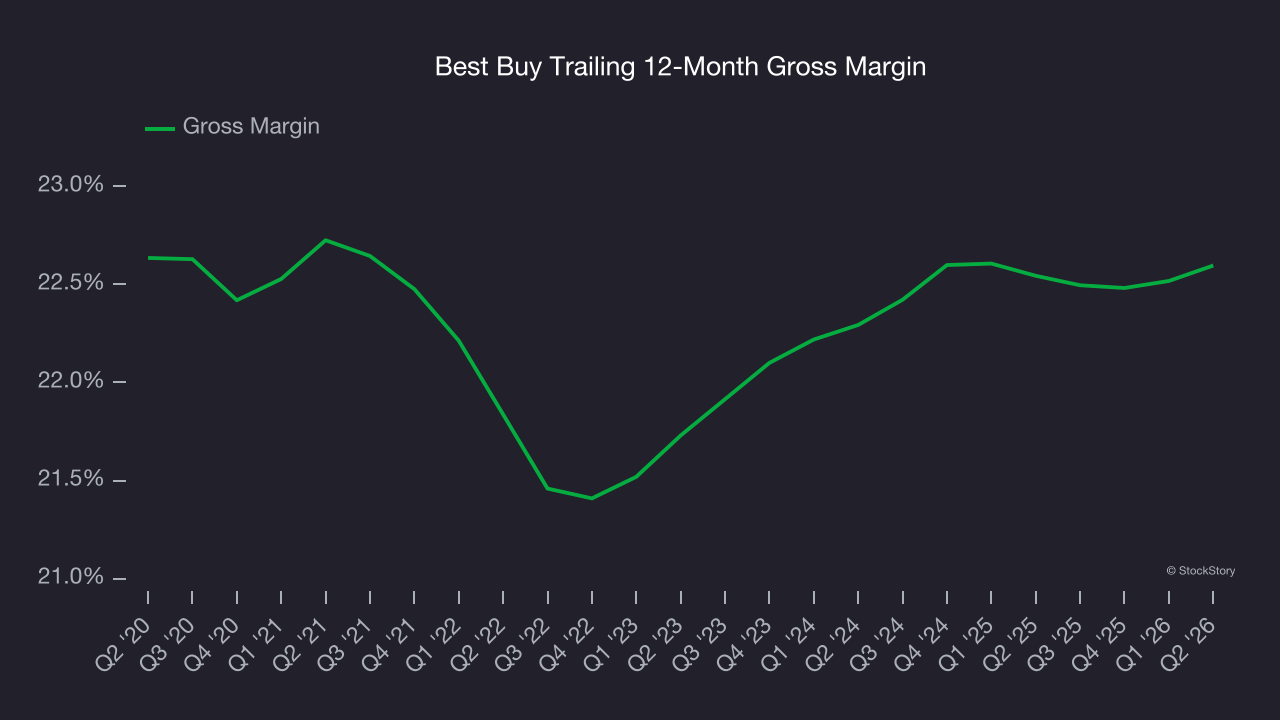
Gross profit margins are an important measure of a retailer’s pricing power, product differentiation, and negotiating leverage.
Best Buy has bad unit economics for a retailer, signaling it operates in a competitive market and lacks pricing power because its inventory is sold in many places. As you can see below, it averaged a 22.6% gross margin over the last two years. That means Best Buy paid its suppliers a lot of money ($77.43 for every $100 in revenue) to run its business.
Final Judgment
Best Buy falls short of our quality standards. After the recent rally, the stock trades at 12.3× forward P/E (or $87.79 per share). This valuation multiple is fair, but we don’t have much confidence in the company. There are better investments elsewhere. We’d recommend looking at a dominant aerospace business that has perfected its M&A strategy.
Stocks We Like More Than Best Buy
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.