

Over the past six months, Starbucks’s stock price fell to $91.86. Shareholders have lost 6.7% of their capital, which is disappointing considering the S&P 500 has climbed by 12%. This might have investors contemplating their next move.
Is there a buying opportunity in Starbucks, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Starbucks Not Exciting?
Even with the cheaper entry price, we’re cautious about Starbucks. Here are three reasons why there are better opportunities than SBUX, plus one stock we’d rather own.
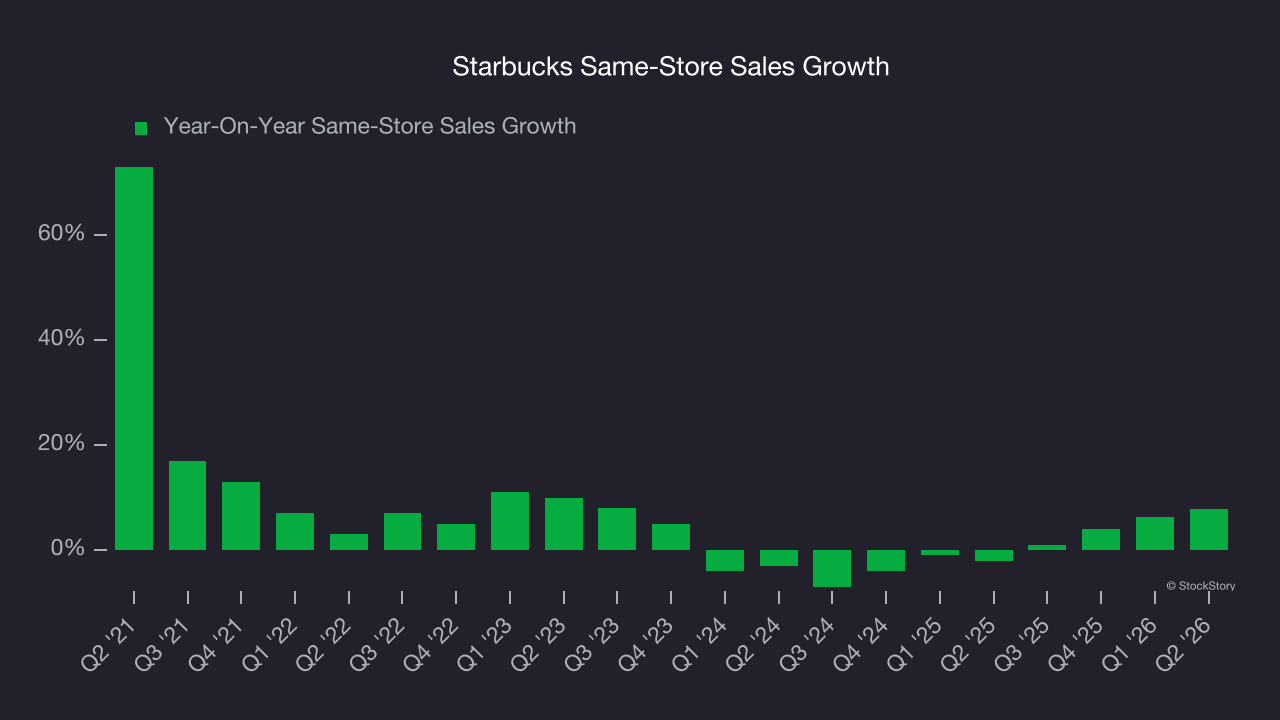
1. Flat Same-Store Sales Indicate Weak Demand
Same-store sales show the change in sales at restaurants open for at least a year. This is a key performance indicator because it measures organic growth.
Starbucks’s demand within its existing dining locations has barely increased over the last two years as its same-store sales were flat.
2. Revenue Projections Show Stormy Skies Ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Starbucks’s revenue to drop by 1.9%, a decrease from its 5.7% annualized growth for the past seven years. This projection is underwhelming and implies its menu offerings will face some demand challenges.
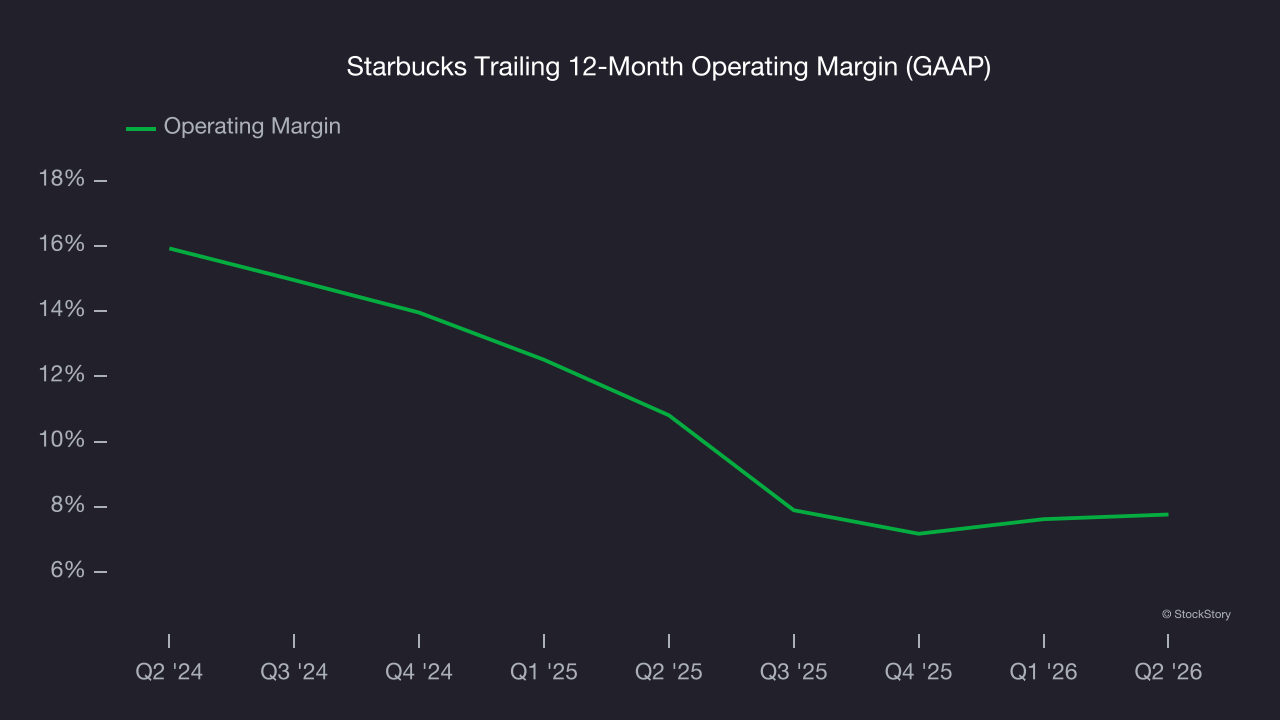
3. Shrinking Operating Margin
Operating margin is a key profitability metric because it accounts for all expenses keeping the business in motion, including food costs, wages, rent, advertising, and other administrative costs.
Analyzing the trend in its profitability, Starbucks’s operating margin decreased by 3 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Its operating margin for the trailing 12 months was 7.8%.
Final Judgment
Starbucks isn’t a terrible business, but it isn’t one of our picks. Following the recent decline, the stock trades at 31.5× forward P/E (or $91.86 per share). This multiple tells us a lot of good news is priced in - we think there are better opportunities elsewhere. We’d recommend looking at an all-weather company that owns household favorite Taco Bell.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.